

Patents
Literature
53 results about "Stock price forecasting" patented technology
Efficacy Topic
Property
Owner
Technical Advancement
Application Domain
Technology Topic
Technology Field Word
Patent Country/Region
Patent Type
Patent Status
Application Year
Inventor
Neural network modelling method
InactiveCN1529281AImprove learning effectImprove generalization abilityPhysical realisationStock price forecastingNerve network
Based on principle of minimization risk of configuration, combined with cooperative collaboration evolution algorithm, and learning network structure of neural network and connection weight value, the invention obtains optimal compromise between network structure and connection weight value finally. The method includes three basic steps: data processing, network learning and network estimated forecast. Configuring network and learning connection weight value are carried out at same time in the invention so as to better solve practical problems existed in traditional neural network learning: correlation between result and initial value, slow convergence rate, easy to run to local minimum value as well as derivable error function needed and over learning. The invention raises learning capability and generalization capability of network, applicable to intelligent diagnosing heart disease, fault diagnosis in industries, stock and goods price forecasting etc.


Owner:SHANGHAI JIAO TONG UNIV
Long and short memory network and depth data cleaning-based financial time sequence prediction method, device and server
InactiveCN110334881AQuick responsePredictableFinanceForecastingStock price forecastingShort-term memory
The invention belongs to the field of financial time series data processing, and discloses a financial time series prediction method, device and server based on a long and short memory network and depth data cleaning, and the method comprises the steps: intercepting stock financial time series data, and carrying out the empirical mode decomposition to obtain an intrinsic mode function sequence; compressing redundant data in the intrinsic mode function sequence by adopting dimension reduction processing; performing unsupervised learning on the data obtained by dimension reduction by adopting astacked automatic encoder to obtain deep features of a financial time sequence; dividing the deep features of the financial time series into a training set, a verification set and a test set in proportion, and training the time recurrent neural network model by using the training set to obtain a trained time recurrent neural network model; and predicting the financial time series according to thetrained time recurrent neural network model. According to the invention, the speed and accuracy of financial prediction are improved by combining the stacked automatic encoder and the long-term and short-term memory network and applying the same to stock price prediction.


Owner:SHENZHEN UNIV
Stock price prediction method and system based on artificial intelligence
InactiveCN108022016AAccurate predictionMarket predictionsFinanceStock price forecastingFeature vector
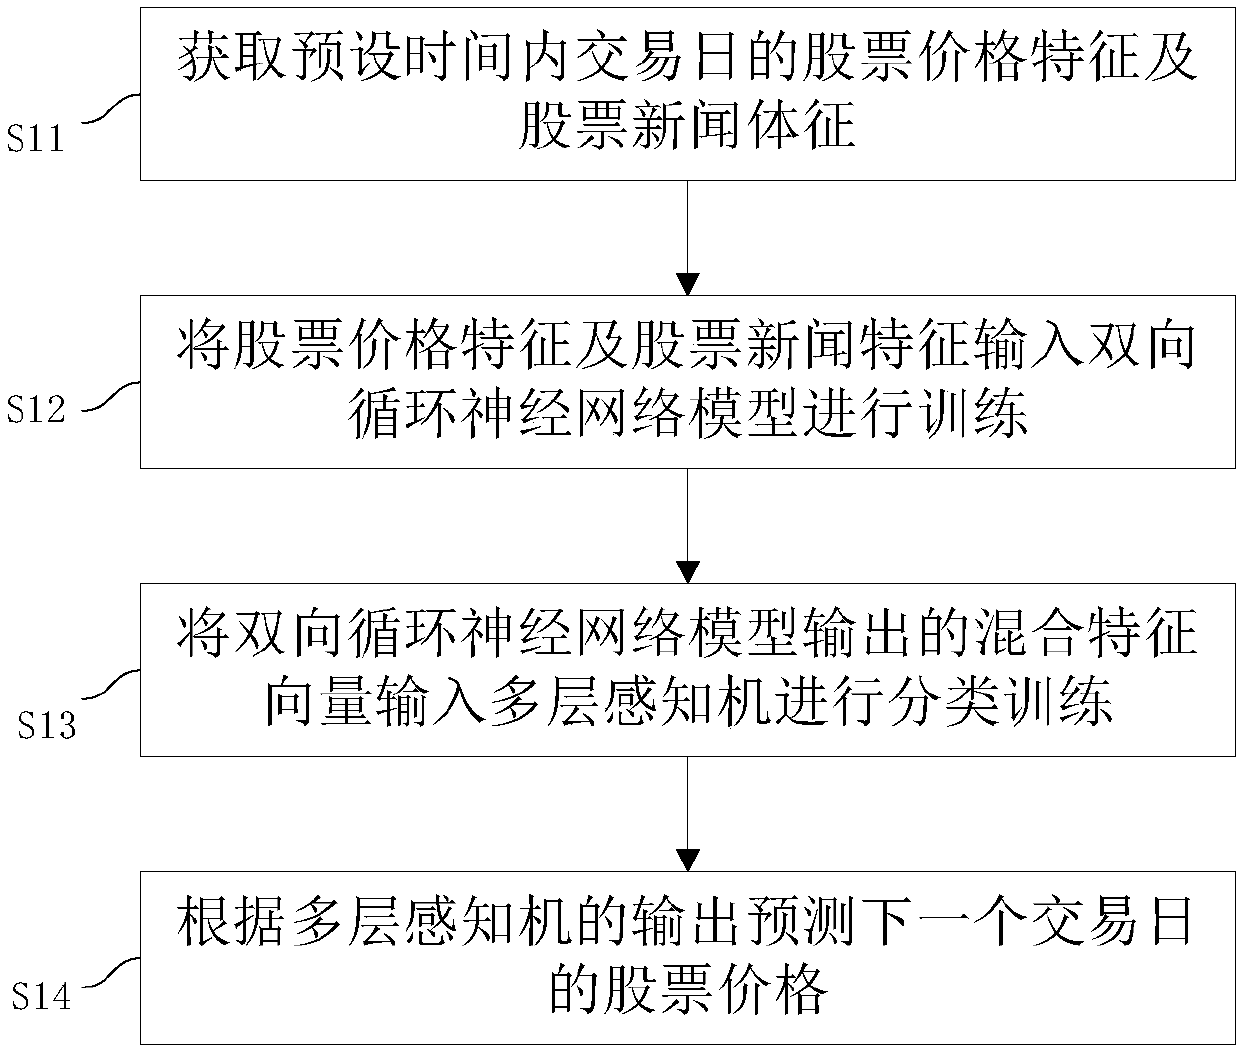
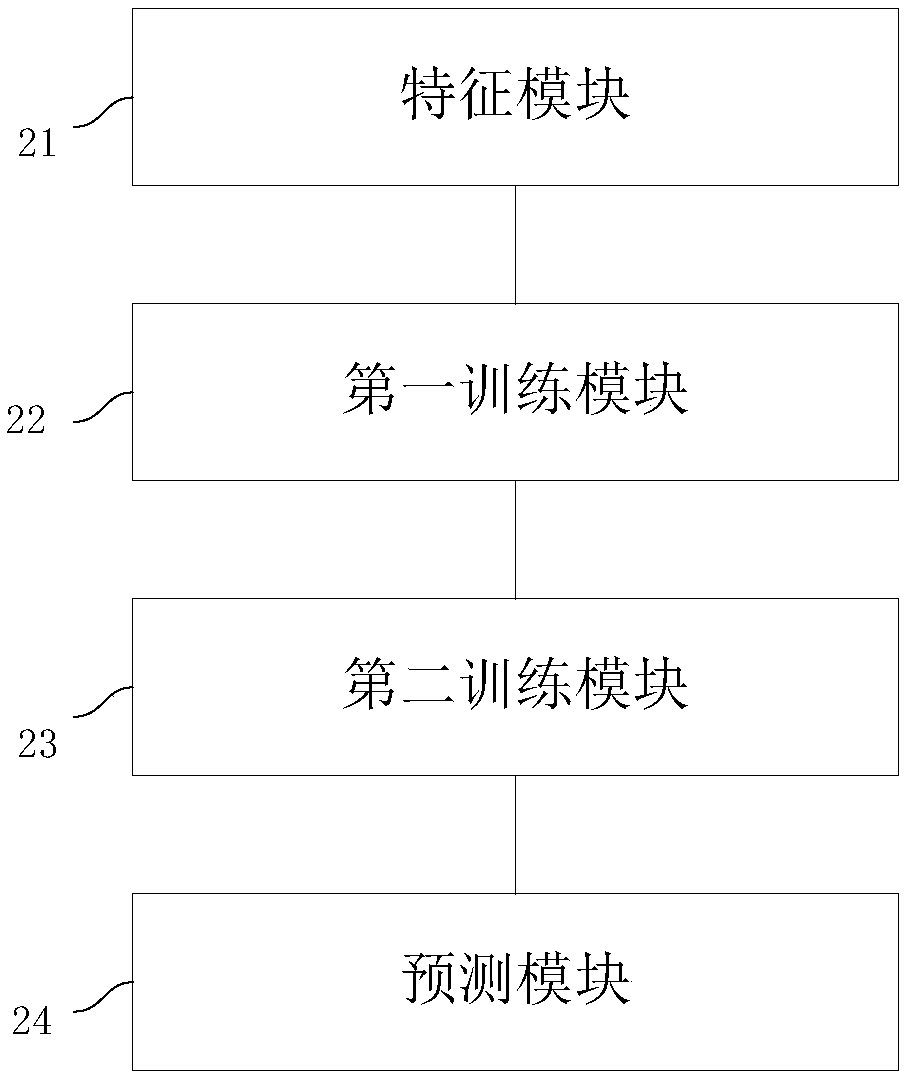
The invention discloses a stock price prediction method and system based on artificial intelligence, so as to solve the problem that considerations of the existing stock prediction are one-sided. Themethod includes the steps of acquiring stock price features and stock news features on a trading day within a preset time; inputting the stock price features and the stock news features into a bidirectional recurrent neural network model for training; inputting a mixed feature vector output by the bidirectional recurrent neural network model to a multi-layer perceptron for classification training;and predicting the stock price on a next trading day based on the output of the multi-layer perceptron. According to the invention, on the basis of a framework of a bidirectional recurrent network, the price features and the news features are combined and the acquired data information is fully utilized to more accurately predict the stock price.
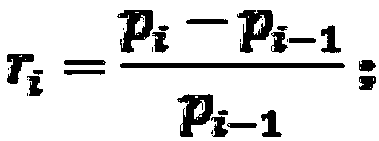
Owner:宏谷信息科技(珠海)有限公司 +1
Stock price prediction method of long-term and short-term memory neural network based on attention mechanism
PendingCN111222992AEasy to predictNon-linear variation is goodFinanceNeural architecturesStock price forecastingEngineering
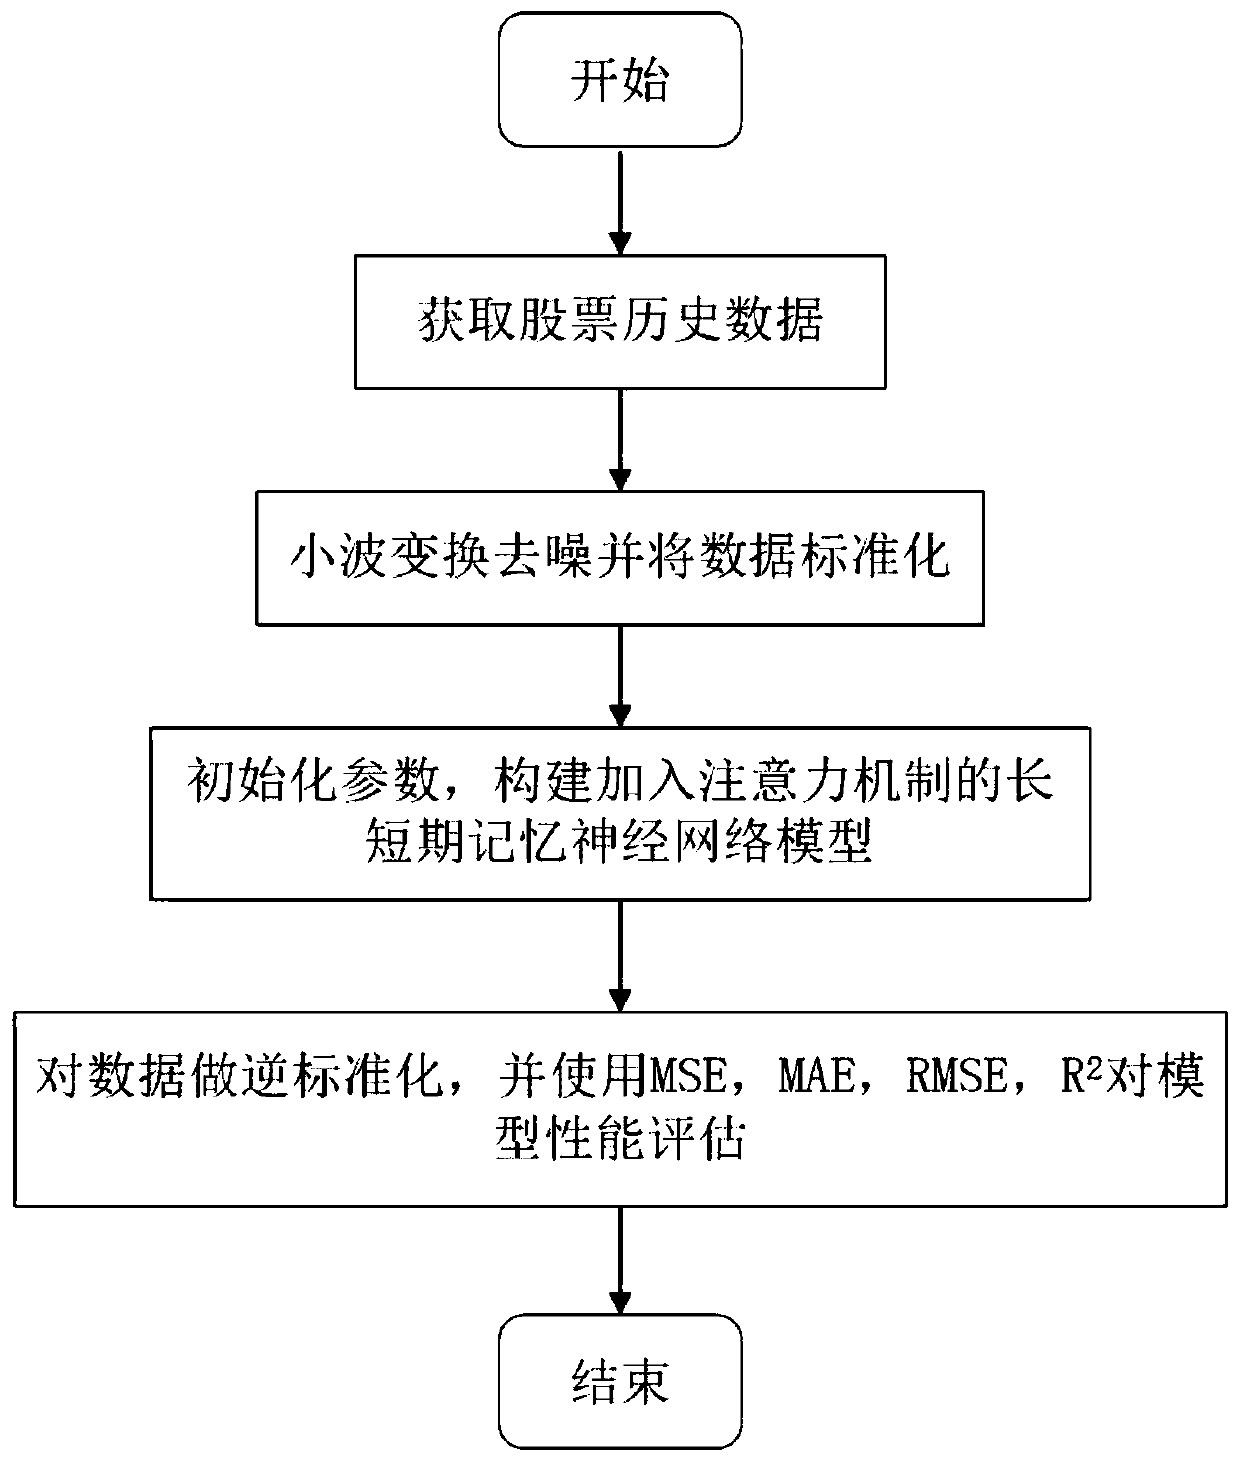
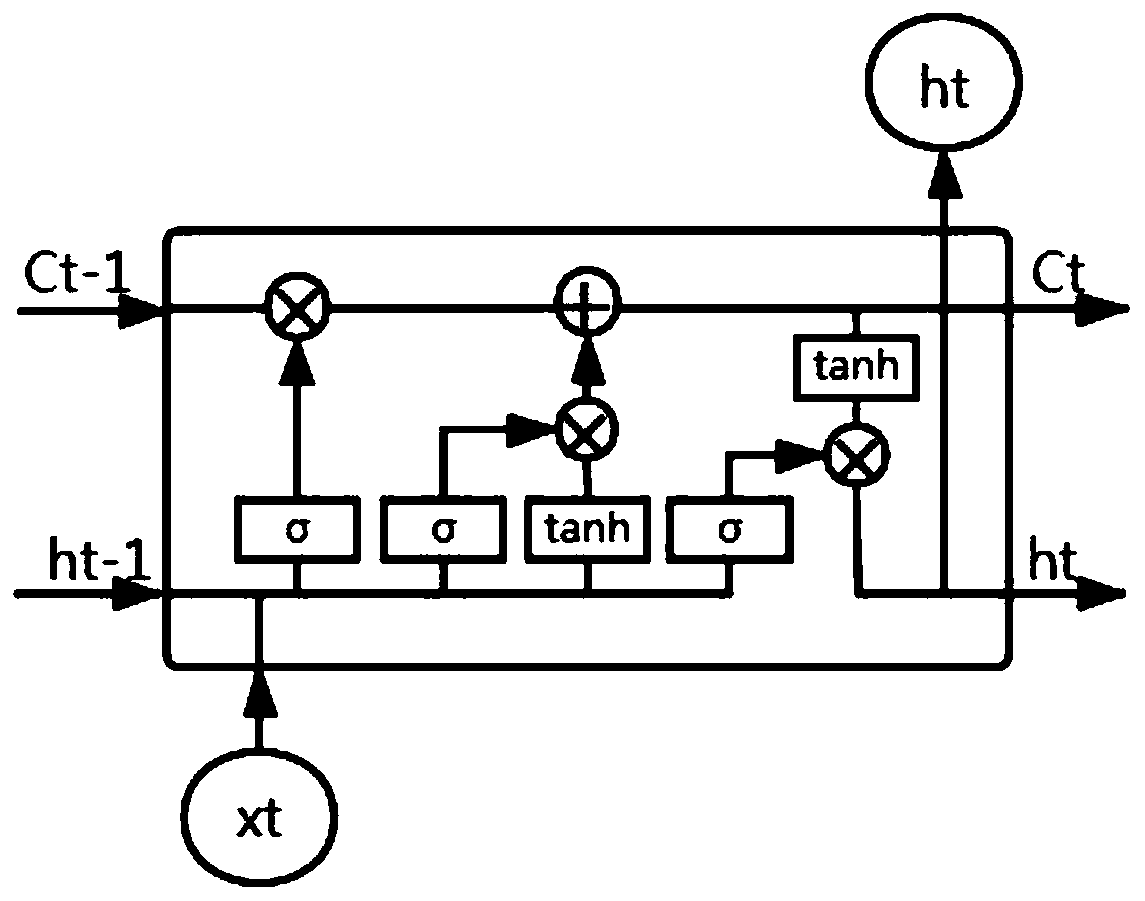
The invention discloses a stock price prediction method based on a long-term and short-term memory neural network of an attention mechanism, and belongs to the field of deep learning and stock prediction. The method comprises the following steps of S1, obtaining stock historical data, performing data preprocessing on the stock historical data, and dividing the stock historical data into a trainingset and a test set; s2, performing data standardization on the training set and the test set, and performing wavelet transform processing on data of the training set to remove noise of the financialsequence; s3, initializing parameters required by the long-term and short-term memory neural network prediction model, constructing the long-term and short-term memory neural network prediction model,adding an attention mechanism layer into the long-term and short-term memory neural network prediction model, and training the long-term and short-term memory neural network prediction model by usingtraining set data; and S4, predicting the test set by using the trained prediction model to obtain a prediction result. According to the invention, the nonlinear change of the stock price can be better predicted.
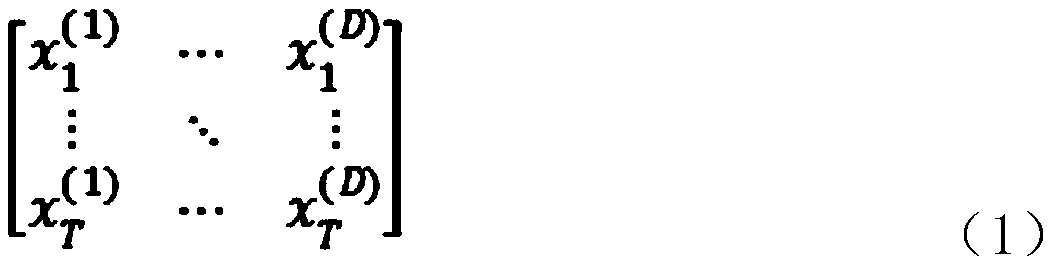
Owner:DALIAN UNIV
Stock prediction method fusing generative adversarial network and two-dimensional attention mechanism
InactiveCN113129148AHigh dependence on foreign tradePredicted target size is largeFinanceForecastingStock price forecastingGenerative adversarial network
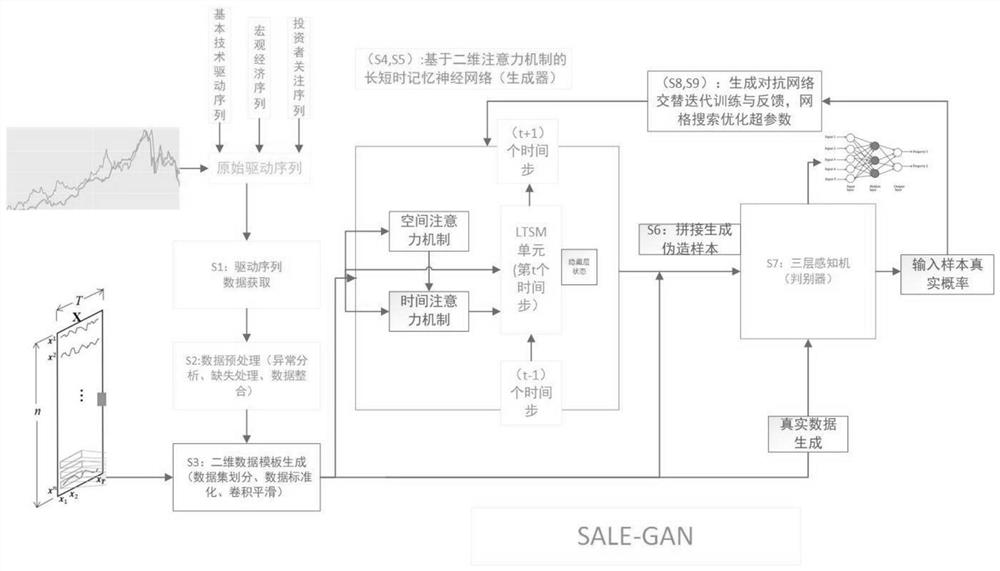
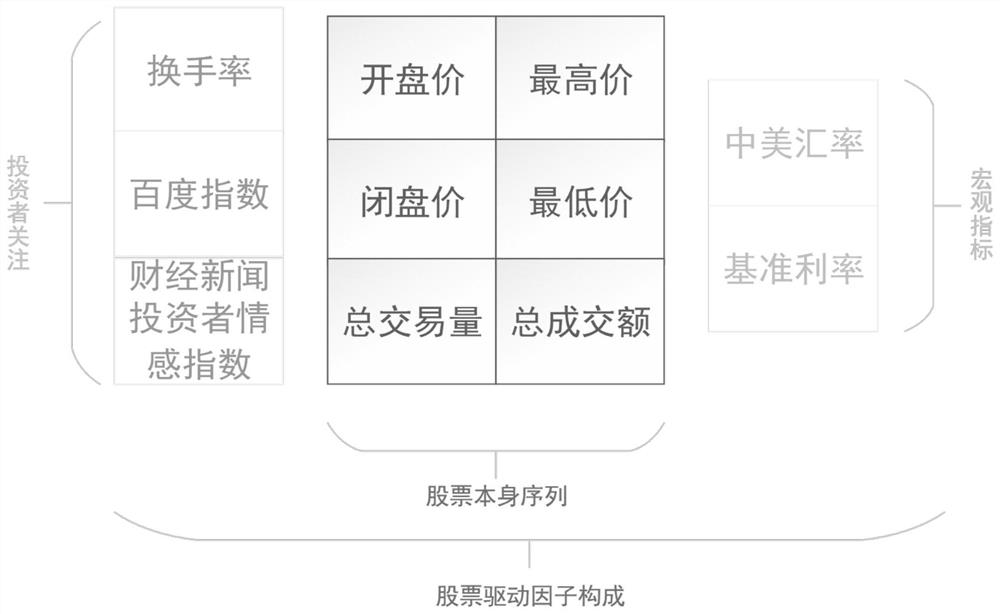
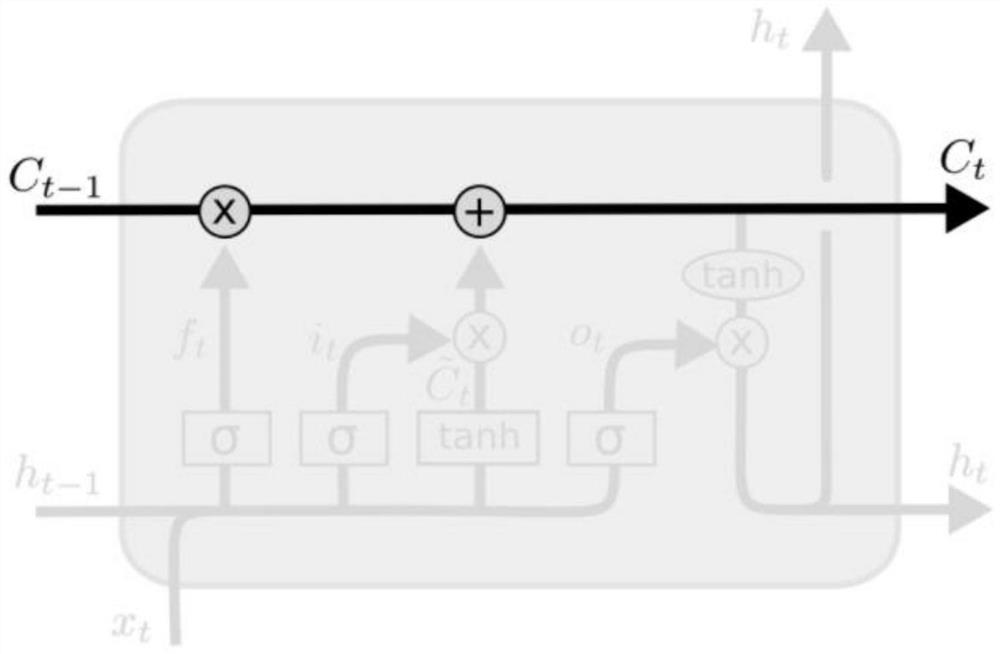
The invention discloses a stock prediction method fusing a generative adversarial network and a two-dimensional attention mechanism. The method comprises the following steps: acquiring historical sequence data of a driving factor as stock sequence input; preprocessing the historical sequence data; divdiing the preprocessed historical sequence data into a training set and a test set, performing standardization, and generating two-dimensional data sequence input; weighting spatial attention of the two-dimensional data sequence input; weighting time attention pf the two-dimensional data sequence input after the space attention weighting; constructing a stock prediction preliminary model based on a two-dimensional time-space attention mechanism as a generator; modifying an output part structure of the generator to obtain a new generator; establishing a stock prediction model based on a newborn generator and a generative adversarial network discriminator; and constructing an optimization target of the stock prediction model to obtain an optimal stock prediction model. According to the invention, a more accurate and ideal stock price prediction result can be generated.
Owner:BEIHANG UNIV
Stock price prediction method of gated cycle unit neural network based on Kalman filtering
PendingCN111210089APredict non-linear changesGood forecastFinanceForecastingStock price forecastingEngineering
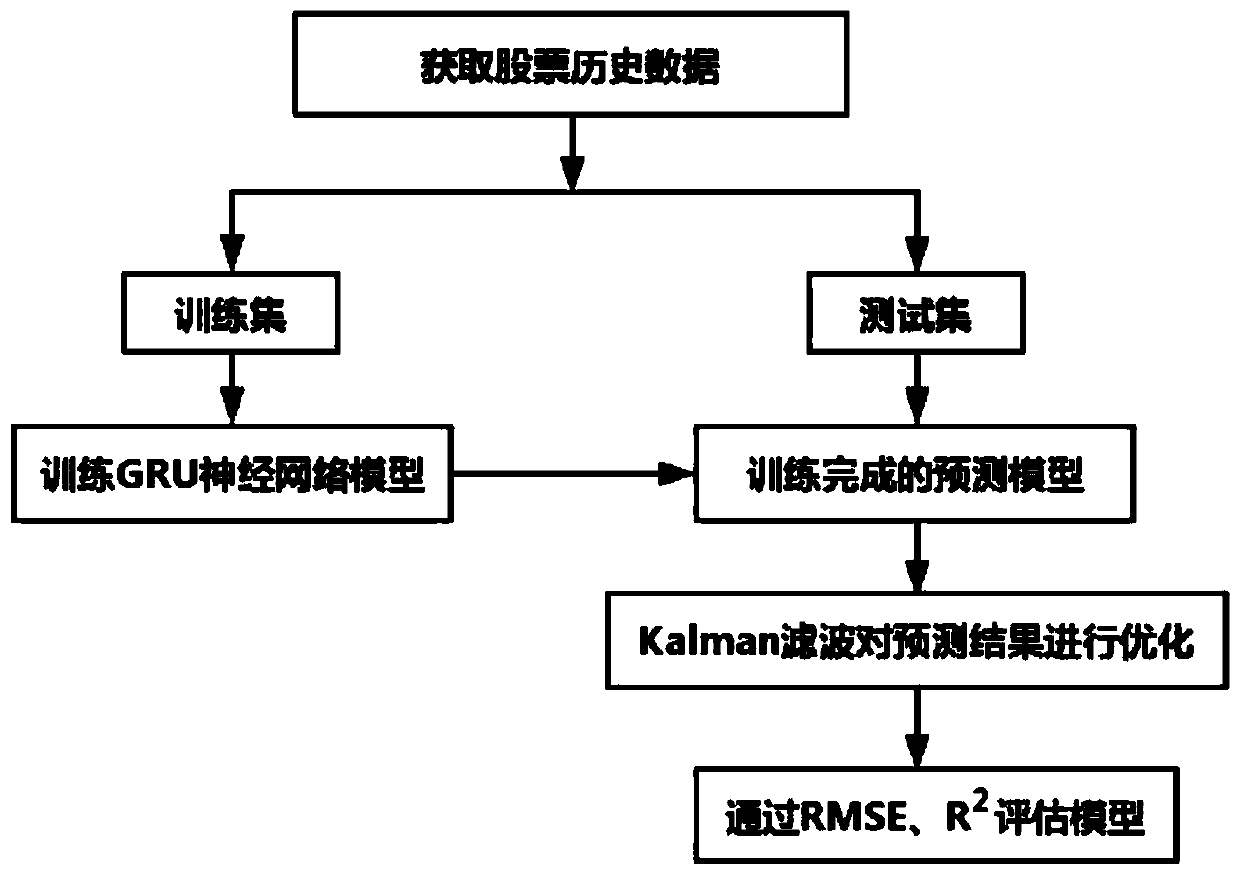
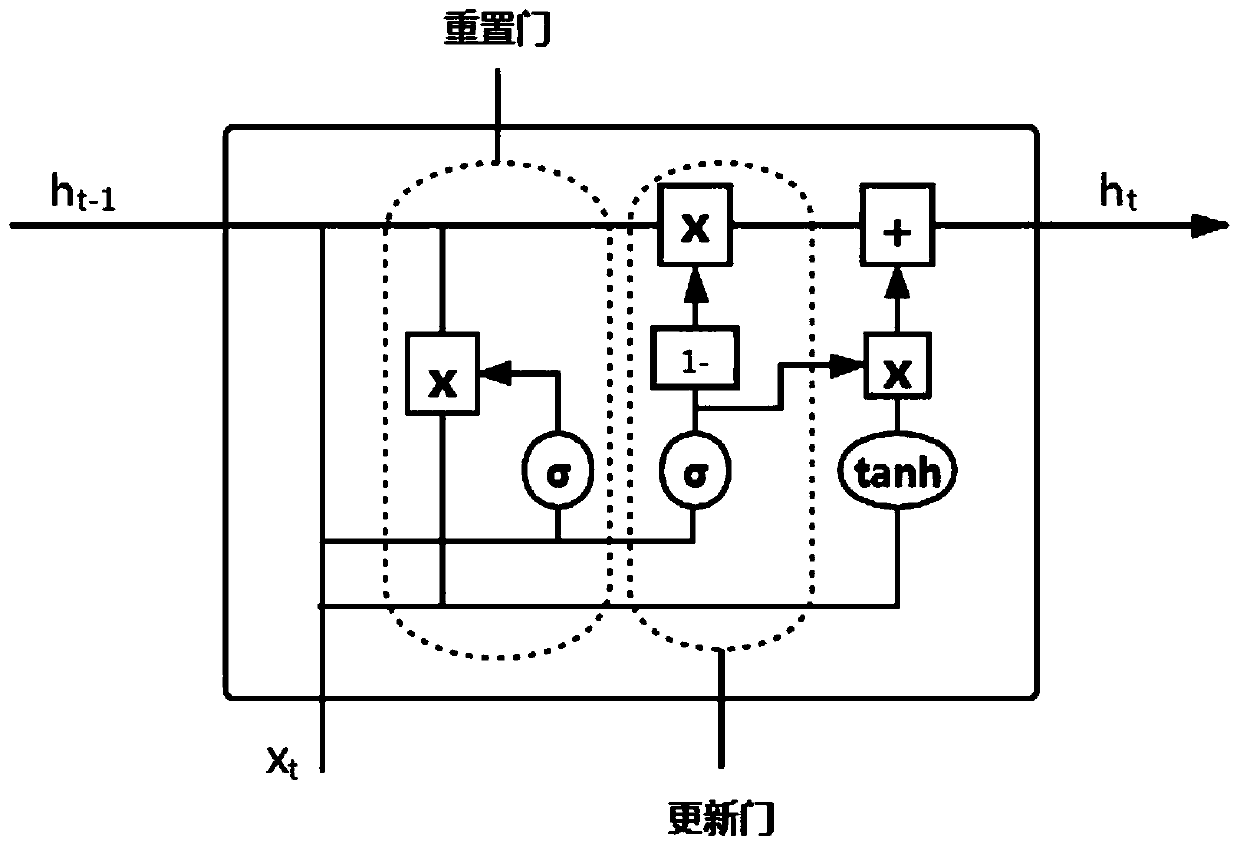
The invention discloses a stock price prediction method of a gated recurrent unit neural network based on Kalman filtering, and belongs to the field of deep learning and stock prediction, and the method comprises the steps: S1, obtaining stock historical data, dividing the data into a training set and a test set, and carrying out the preprocessing; S2, initializing parameters required by prediction of the gating cycle unit neural network, constructing a gating cycle unit neural network model, and training and storing the gating cycle unit neural network model; S3, using the trained predictionmodel to predict the test set data, and using a Kalman filtering algorithm to perform denoising optimization on the obtained prediction result sequence; and S4, evaluating the performance of the prediction model for the denoised and optimized result in S3 by using the root-mean-square error and the determination coefficient. The stock price is predicted through the gating cycle unit neural network, and the prediction result sequence and the true value are compared and optimized by using the Kalman filtering algorithm so as to achieve the more accurate prediction effect.
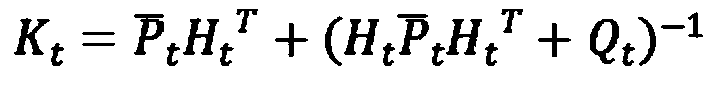
Owner:DALIAN UNIVERSITY
Stock price prediction method and device based on wavelet transform and long-term and short-term memory neural network fusion
InactiveCN110610419ASolve problemsSolve the contradiction of time-frequency localizationFinanceForecastingStock price forecastingSequence analysis
The invention provides a stock price prediction method and device based on wavelet transform and long-term and short-term memory neural network fusion, and effectively solves the contradiction of time-frequency localization by introducing a variable scale factor and a translation factor compared with Fourier transform. Wavelet transformation is used for analyzing local information of frequency intime and space; multi-scale and multi-aspect refinement is carried out on the time sequence through stretching and translation operation, the purpose of frequency subdivision can be finally achieved,the requirement of time sequence analysis can be automatically met, the method can be focused on any aspect of the time sequence, and the problem of Fourier transform difficulty is solved. The LSTM has better performance in a longer sequence by increasing the connection of cell states, and effectively solves the problems of gradient disappearance and gradient explosion of the RNN along with the increase of the number of hidden layers. Wavelet transformation and a long-short-term neural network are fused, prediction errors are reduced through modeling of frequency information, and prediction precision is improved.


Owner:SHANDONG UNIV OF FINANCE & ECONOMICS
Event-driven stock price prediction method, device and equipment and storage medium
PendingCN109657851AImprove accuracyAdapt to rapid changeFinanceForecastingStock price forecastingStock trend prediction
The invention discloses an event-driven stock price prediction method and device, equipment and a storage medium, and the method comprises the steps: selecting a stock associated with a current news event based on the current news event; And predicting price fluctuation of the stock by adopting a heterogeneous information collaborative network model based on the current news event and historical financial time sequence data of the stock. According to the method, the current news event and the historical financial time sequence data of the selected stock are input into the heterogeneous information collaborative network model, so that the price trend of the selected stock can be obtained, and the future trend of the stock price can be predicted. The heterogeneous information collaborative model is combined with the historical price trend of the stock and the interest and goodness characteristics of news, and the stock price prediction accuracy can be improved. The method is convenient to use, high in efficiency and suitable for rapid change of the financial market. The method can be widely applied to stock selection and stock trend prediction according to various news events.


Owner:HARBIN INST OF TECH SHENZHEN GRADUATE SCHOOL
Neural network modelling method
InactiveCN1251136CImprove learning effectImprove generalization abilityPhysical realisationStock price forecastingNerve network
Based on principle of minimization risk of configuration, combined with cooperative collaboration evolution algorithm, and learning network structure of neural network and connection weight value, the invention obtains optimal compromise between network structure and connection weight value finally. The method includes three basic steps: data processing, network learning and network estimated forecast. Configuring network and learning connection weight value are carried out at same time in the invention so as to better solve practical problems existed in traditional neural network learning: correlation between result and initial value, slow convergence rate, easy to run to local minimum value as well as derivable error function needed and over learning. The invention raises learning capability and generalization capability of network, applicable to intelligent diagnosing heart disease, fault diagnosis in industries, stock and goods price forecasting etc.


Owner:SHANGHAI JIAOTONG UNIV
Stock price prediction method and system fusing text multi-theme information, and medium
ActiveCN110363568AEfficient integrationMarket predictionsFinanceStock price forecastingEncoder decoder
The invention provides a stock price prediction method and system fusing text multi-theme information and a medium, and the method comprises the steps: a data preprocessing step: obtaining text data and stock data, carrying out the preprocessing of the obtained text data and stock data, and obtaining the preprocessed data; and a model training step: training a stock price prediction model according to the obtained preprocessed data to obtain a trained model. According to the method, a multi-head attention mechanism is used for mapping text vectors to different semantic spaces, then theme information is extracted, and finally different attention weights are ingeniously used for fusing different theme information. In addition, text information and stock price information are effectively fused into a unified framework by utilizing an encoder and decoder framework, so that the influence of different time nodes on stock price prediction can be dynamically adjusted.


Owner:SHANGHAI JIAO TONG UNIV
Organization and individual stock comment accuracy rating method
The invention discloses an organization and individual stock comment accuracy rating method and belongs to the technical field of credit rating. The organization and individual stock comment accuracy rating method includes: dividing organization or individual rates into five stars according to comprehensive accuracy P of organization or individual stock comments, wherein the comprehensive accuracy P of the organization or individual stock comments is the arithmetic mean value of annual EPS (earnings per share) accuracy and stock price accuracy judged by the organization or individual on all stocks with the stock comments; setting the annual EPS or stock price predicted on a certain stock by the organization or individual to conform to normal distribution N (mu, sigma <2>), wherein when the annual EPS or the stock price predicated value judged on the certain stock by the organization or individual is X, annual EPS or stock price accuracy predicated on the certain stock is the proportion of a curve area, out of a range from (mu-lmu-Xl) to (mu+lmu-Xl) on a normal distribution function N(mu, sigma <2>) curve horizontal axis, to the total area. The organization and individual stock comment accuracy rating method can be used for predicting and rating the accuracy of the stock comments released by security companies or individuals.


Owner:王志恒
Share price prediction method based on mixed algorithm of Monte Carlo and grey prediction
InactiveCN103337034AEffective Investment Operation SuggestionsFinanceStock price forecastingOriginal data
The invention discloses a share price prediction method based on a mixed algorithm of Monte Carlo and grey prediction. The share price prediction method is characterized by comprising the following steps: step 1, acquiring original data time series and risk-free interest rate; step 2, utilizing the assembly language of the Monte Carlo to simulate short-term security price; step 3, creating grey prediction model, and utilizing the assembly language of grey prediction to predict short-term security price; step 4, multiplying the results predicted by the two methods by respective weight to obtain the mixed prediction of final security price; the proportions of the weights are determined through a plurality of stock market prediction experiments; step 5, testing error: the prediction accuracy can be obtained by testing the error between the prediction value and the true value. According to the invention, the mixed algorithm of Monte Carlo and grey prediction is utilized to predict the share price, short-term prediction can be made on the market index or individual share price, and the method can provide massive investors with effective suggestions on investment operation.
Owner:ANHUI QINGXIN SOFTWARE TECH
Stock price prediction method based on LSTM neural network
PendingCN113095484APrediction is stableImprove accuracyFinanceForecastingStock price forecastingEngineering
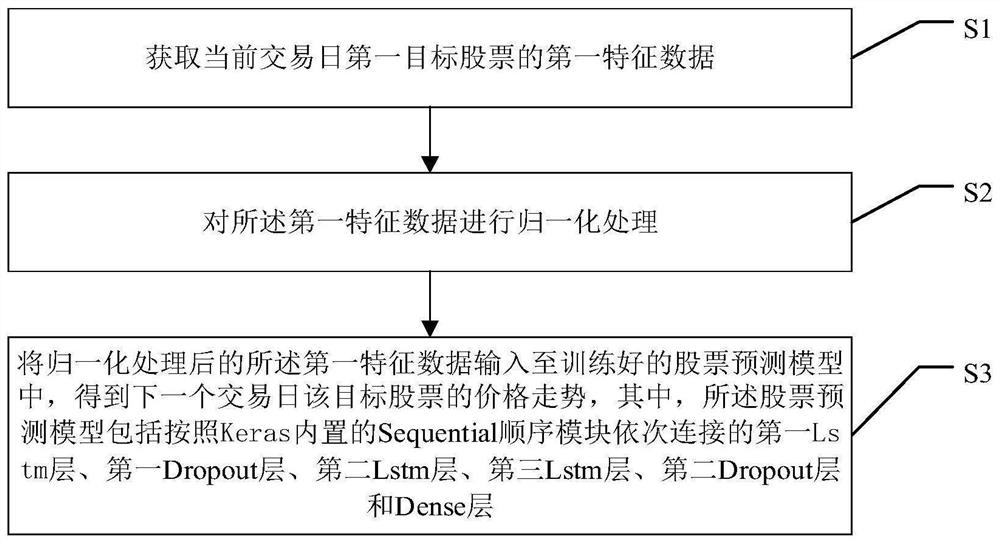
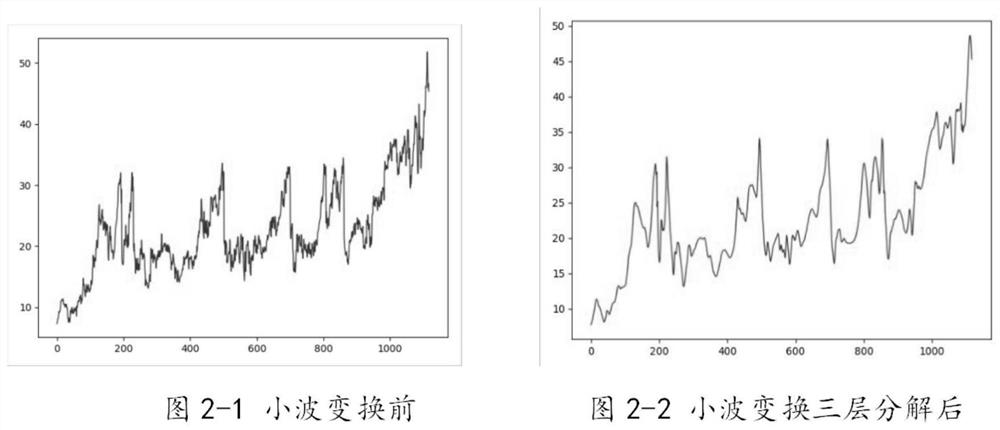
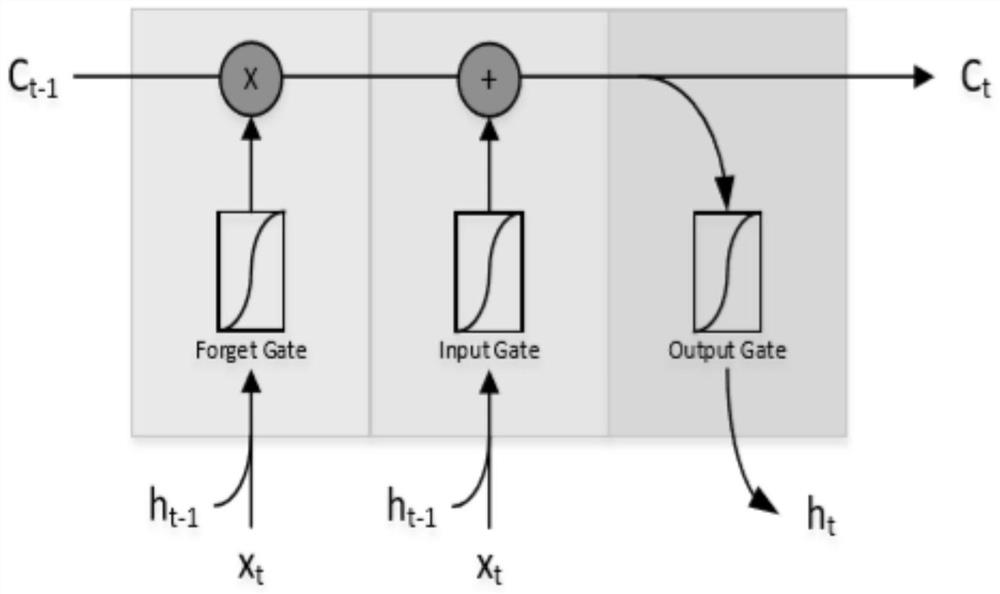
The embodiment of the invention relates to a stock price prediction method based on an LSTM neural network. The stock price prediction method based on the LSTM neural network comprises the steps of obtaining first feature data of a first target stock on a current trading day; performing normalization processing on the first feature data; inputting the first feature data after normalization processing into a trained stock prediction model to acquire the price trend of the target stock on the next trading day, wherein the stock prediction model comprises a first Lstm layer, a first Dropout layer, a second Lstm layer, a third Lstm layer, a second Dropout layer and a Dense layer, which are sequentially connected according to a Sequence sequence module built in Keras. According to the stock price prediction method based on the LSTM neural network provided by the embodiment of the invention, the accuracy of predicting the rising and falling trend of the stock is obviously improved, and the prediction effect of the LSTM network model tends to be stable along with the increase of historical stock data.
Owner:SOUTH CHINA NORMAL UNIVERSITY
Financial stock prediction method fusing clustering and ensemble learning
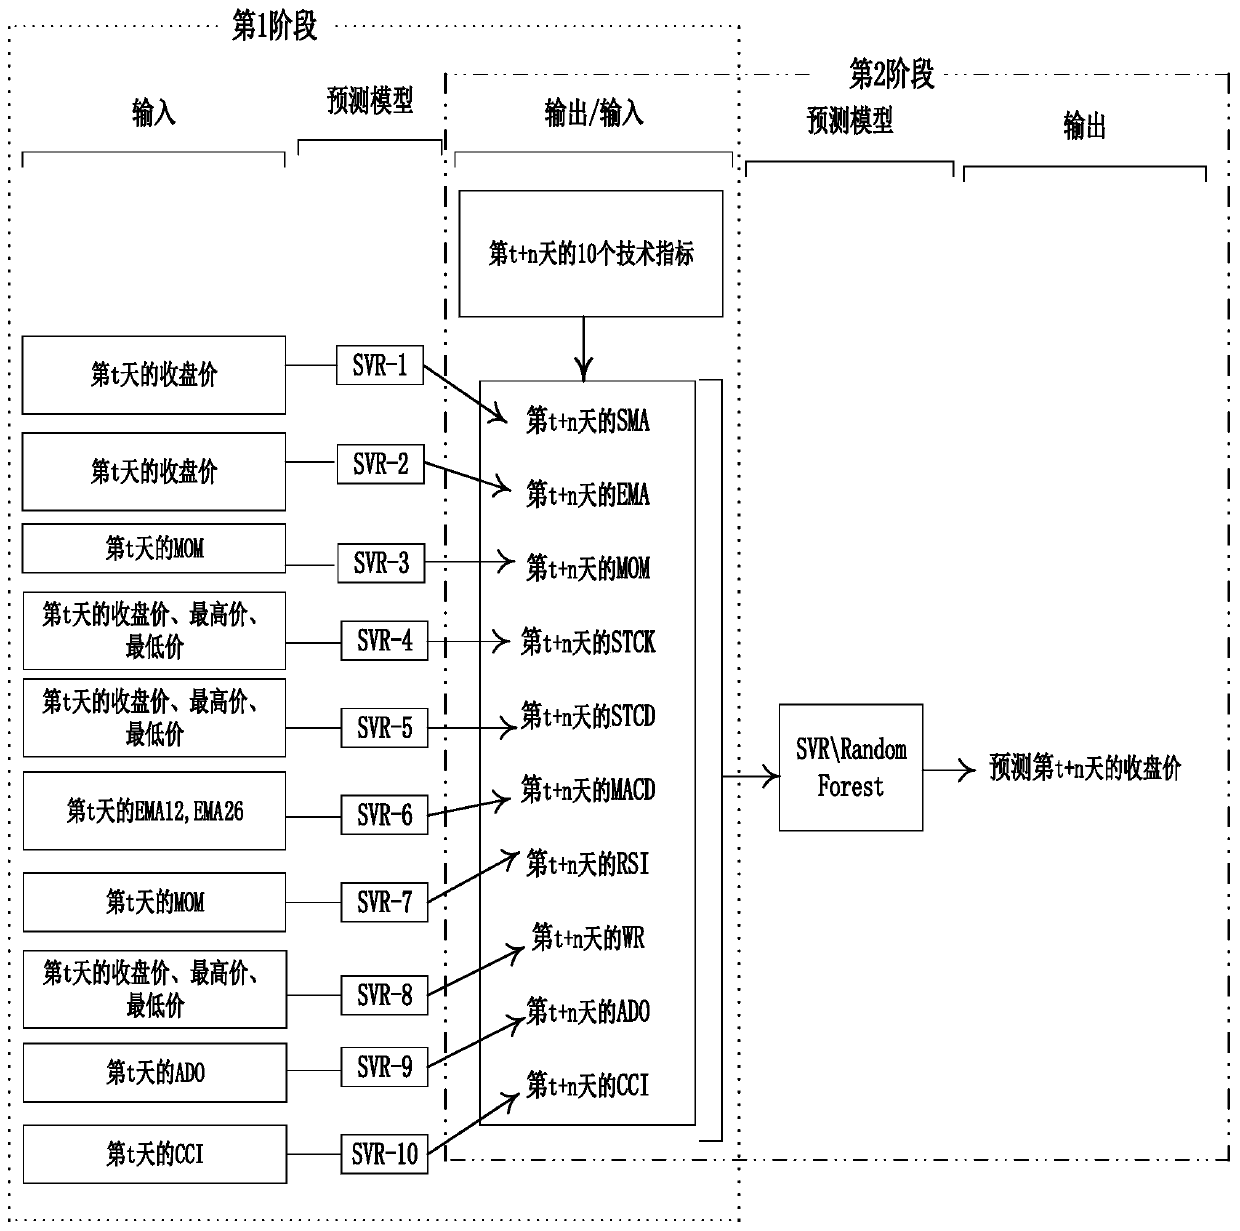
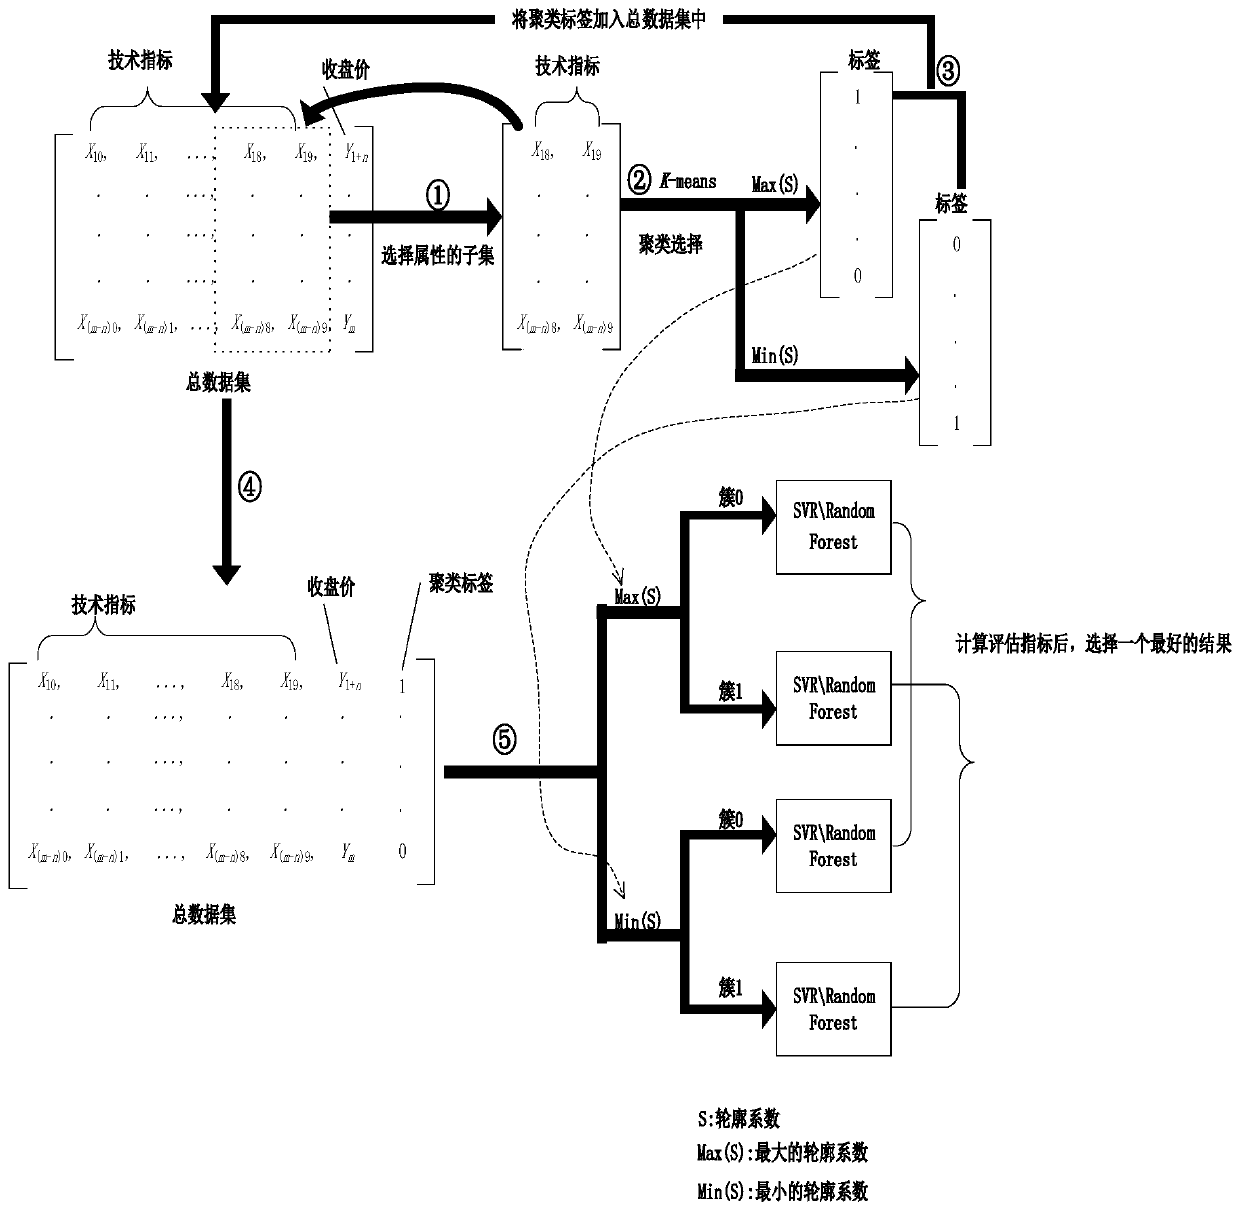
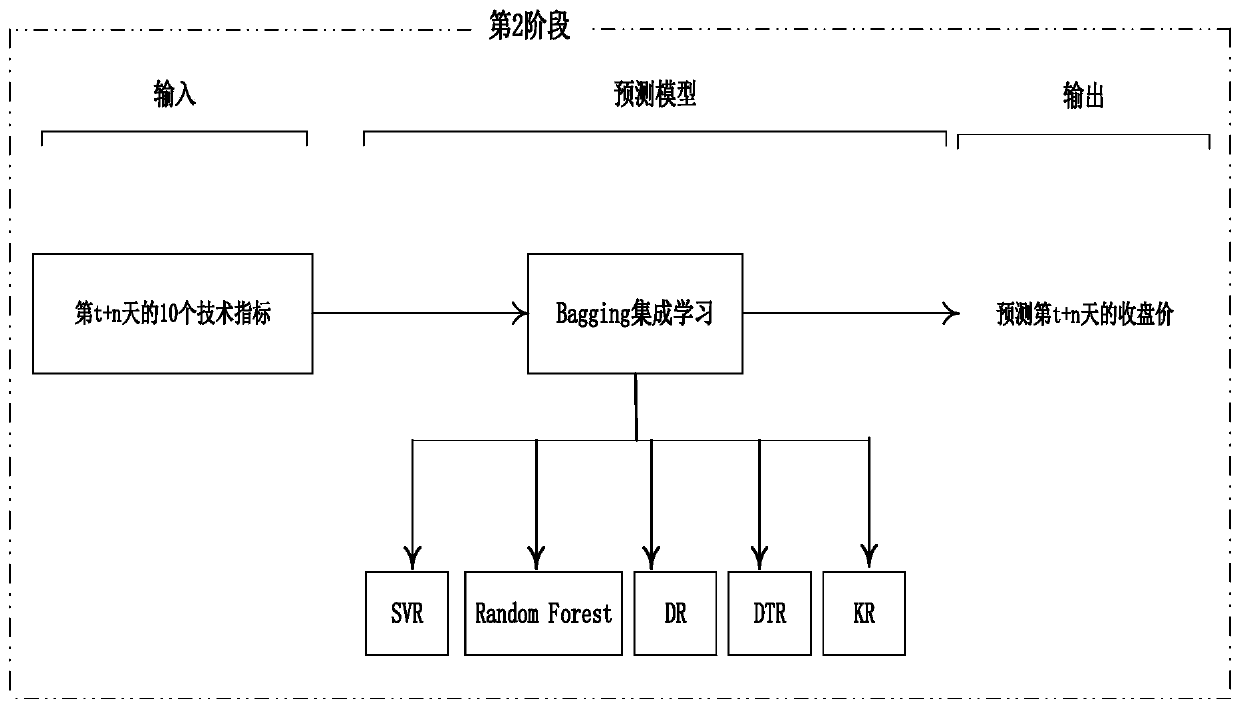
The invention discloses a financial stock prediction method fusing clustering and ensemble learning. According to the method, a k-means clustering method is adopted to cluster a plurality of common technical indexes, so that a C-SVR-SVR (Clustering-SVR-SVR) prediction model and a C-SVR-RF (Clustering-SVR-RF) prediction model based on clustering can be provided; and then, a Bagging ensemble learning algorithm is adopted to propose a model E-SVR&RF (Ensemble-SVR&RF). And finally, the k-means clustering algorithm and the Bagging ensemble learning algorithm are combined, and a hybrid model C-E-SVR&RF (Clustering-Ensemble-SVR&RF) is provided. According to the invention, four Chinese stocks, namely SPD Bank (SH: 600000), CITIC Securities (SH: 600030), ZTE Corporation (SZ: 000063) and Le (SZ: 300104), are selected for experimental evaluation. Experimental results show that the C-SVR-SVR and the C-SVR-RF model of the k-means clustering algorithm are independently added, the prediction accuracyof the specific stock price can be improved, but the overall effect is not obvious. And the accuracy of stock price prediction can be improved by independently adding the ensemble learning algorithm.And a k-means clustering algorithm and an ensemble learning hybrid algorithm are fused, so that the stock price prediction accuracy can be further improved, and particularly, the prediction can be advanced by 20 and 30 days.
Owner:HUNAN UNIV
Stock price prediction method and system based on improved LSTM
InactiveCN109272406AImprove predictive performanceBig amount of dataFinanceBiological neural network modelsStock price forecastingData acquisition
The invention discloses a stock price prediction method based on an improved LSTM. The method comprises the following steps: S1, acquiring historical data with different characteristics at different time points of stock trading, and selecting training data based on actual prediction needs; 2, inputting training data, constructing a stock price prediction model based on the deep learning theory andusing a multi-layer LSTM neural network, and training the stock price prediction model; S3, outputting a prediction result, combining the real value and taking the error percentage as the evaluationindex to carry on the evaluation. The system includes a data acquisition and selection module, a model construction and training module and a prediction and evaluation module. The invention utilizes the multi-layer LSTM neural network to construct the stock price prediction model, obtains the stock historical data with different characteristics at a plurality of time points at one time, greatly increases the amount of data, and trains the stock price prediction model by using the training data, so that the stock price prediction model can show more scenes, and thus the prediction effect of themodel is greatly improved.


Owner:安徽磐众信息科技有限公司
Stock price prediction method and device
The invention provides a stock price prediction method and device, and the method comprises the steps: carrying out the clustering of the historical data of a stock price based on a data clustering type, obtaining a plurality of types of historical data, wherein the historical data to comprise a first proportion of training set data; based on each type of training set data, respectively constructing an echo state network model corresponding to each type of historical data; and respectively inputting each type of historical data into the corresponding echo state network model to obtain a stockprice prediction result corresponding to each type of historical data.


Owner:BANK OF CHINA
A stock price prediction method based on an APSO-BP neural network
InactiveCN109919374AStrong local search abilityImprove global search performanceFinanceForecastingStock price forecastingNetwork model
The invention discloses a stock price prediction method based on an APSO-BP neural network, which comprises the steps of data preprocessing and APSO-BP neural network prediction model construction. The method comprises the following steps: firstly, extracting effective features from collected stock data, and performing data preprocessing to form a feature data sample set; Then, constructing an appropriate BP neural network model; optimizing the initial weight and the threshold value of the BP neural network by using an adaptive mutation particle swarm optimization (APSO) algorithm to obtain the final APSO-BP neural network prediction model. The method is higher in prediction precision, does not fall into a local extreme value, is high in convergence speed, is short in prediction time, andis higher in execution efficiency.


Owner:HANGZHOU DIANZI UNIV
Group decision stock price trend insight method based on graphic feature library
InactiveCN111967685AImprove universalityImprove versatilityFinanceForecastingStock price forecastingEngineering
Stock price estimation belongs to the field of financial big data analysis and stock investment. An existing stock price prediction method either lacks reasonable mathematical interpretability (such as stock price prediction based on deep learning) or is difficult to evolve a model in real time according to the time sequence change of the stock price. The invention discloses a group decision stockprice trend insight method based on a graphic feature library. The method aims to construct a stock price or a graphic feature library after standardized mapping through stock transaction historicaldata. And after the to-be-predicted stock is subjected to standardization and wavelet de-noising smoothing, similarity calculation is performed on the graphical to-be-predicted stock and graphs in thegraph feature library by adopting a dynamic time warping algorithm, and a group decision algorithm is introduced to estimate the future stock price of the target stock by using the similar graphs. The minimized construction of the graphic feature library directly influences the precision and efficiency of stock price prediction; the problem is an NP problem, the invention provides a heuristic algorithm based on a greedy strategy to realize approximation of minimization of a graphic feature library, and a graphic base in the graphic feature library can be adaptively adjusted according to incremental change of financial data.


Owner:山西墨丘利科技有限公司
Stock prediction method based on time convolution network fusion channel attention mechanism
PendingCN119313467Aincrease prominencecooperate wellFinanceInternal combustion piston enginesStock price forecastingNetwork Convergence
The embodiment of the invention relates to a stock prediction method based on a time convolution network fused channel attention mechanism. The stock price prediction method provided by the embodiment of the invention comprises the steps of obtaining feature data of a target stock on a current trading day; performing normalization processing on the feature data; the feature data after normalization processing is input into a trained stock prediction model, the price trend of the target stock on the next trading day is obtained, the stock prediction model comprises a channel attention mechanism added behind each basic TCN residual error block, and a channel attention mechanism is added behind each basic TCN residual error block; an original TCN network can capture a longer time sequence relation by using a smaller convolution kernel, and attention of convolution channels can be enhanced after a channel attention mechanism is fused, so that important feature information of each channel is captured. According to the stock prediction method based on the time convolution network and the attention mechanism in the embodiment of the invention, various evaluation indexes such as MAE and RMSE are obviously reduced.

Owner:HARBIN UNIV OF SCI & TECH
Short-term stock price forecasting system that integrates GRU and XGBoost for advanced time series forecasting
A computer-implemented system for short-term stock price prediction, consisting of: • a data acquisition module (101) configured to retrieve historical intraday stock data including closing prices, trading volumes and technical indicators; • a data preprocessing module (102) configured to normalize the data and generate temporally consecutive samples using a sliding window approach; • a neural network module (103) comprising a Gated Recurrent Unit (GRU) architecture configured to receive the temporally consecutive samples and output intermediate stock price predictions; • a gradient boosting module (104) comprising an Extreme Gradient Boosting (XGBoost) regressor configured to receive the output of the GRU module along with associated residual features and to refine the predictions by modeling nonlinear patterns and residual errors; • and an output module (105) configured to present the final refined stock price prediction, where the GRU module is trained to minimize a loss function for the mean squared error, and the XGBoost module is trained to minimize an objective function for the squared error, thereby providing improved predictive accuracy for financial time series forecasts.

Owner:PATTNAIK PRASANT KUMAR PROF BHUBANESWAR +3
Stock price prediction method and system based on technical indexes and news emotion
InactiveCN111695998AAchieve forecastHigh precisionFinanceSemantic analysisStock price forecastingPrice prediction
The invention discloses a stock price prediction method and system based on technical indexes and news emotion in the technical field of computer information technology processing and financial engineering, and aims to solve the technical problem that the stock price cannot be accurately predicted by efficiently utilizing various information source information including financial news in the priorart. The method comprises the following steps: solving a news emotion feature time sequence of a target stock based on financial news text corpus related to the target stock; generating a market snapshot sequence set of the target stock based on the news emotion feature time sequence and a pre-acquired technical index feature time sequence; matching the market snapshot sequence set with the yieldof the target stock to obtain a return rate prediction function of the target stock; and predicting the return rate of the target stock based on the pre-acquired market snapshot and the return rate prediction function of the target stock.


Owner:HOHAI UNIV
Stock price prediction method and system
The invention provides a stock price prediction method and system. The management method comprises: obtaining stock transaction data in a preset first time period; analyzing the stock transaction data to form a stock price trend chart; obtaining a stock price prediction instruction of a user; and based on the stock price prediction instruction and the stock transaction data, predicting the stock price, and determining a system prediction price. According to the stock price prediction method, data such as stock transaction data are comprehensively analyzed according to the stock price prediction instruction of the user, the stock price is predicted, data prediction is provided for stock purchase of the user, and stock purchase decision making of the user is facilitated.


Owner:NANJING UNIV OF AERONAUTICS & ASTRONAUTICS
Stock price trend prediction method
The invention discloses a stock price trend prediction method. The method comprises: firstly, a stock price prediction model is constructed based on an LSTM recurrent neural network model to predict astock price; introducing a fuzzy comprehensive evaluation algorithm; the prediction result of the stock price is evaluated; prediction results of important attributes in the main stock prices are highlighted; Enabling models more reliable, the final prediction result is more accurate; According to the method disclosed by the invention, the memory function of the recurrent neural network is utilized; According to the method, the influence of the current influence factor on the stock price change at the next moment or after longer time is captured, then the stock price predicted by the recurrent neural network is comprehensively evaluated through the fuzzy comprehensive evaluation algorithm, the importance of main factors is highlighted, and the finally predicted stock price trend has higher precision.


Owner:CHONGQING UNIVERSITY OF SCIENCE AND TECHNOLOGY
Stock price prediction system and stock price prediction program
We provide a stock price prediction system and program that accurately grasps trends in stock price fluctuations. [Solution] The stock price prediction system 10 comprises a reference value setting unit 11 that obtains the closing stock price on a reference date for the company to be predicted and sets the stock price as the reference value; a stock price acquisition unit 12 that obtains the company's daily closing stock price over a specified period as daily stock prices and stores them in a recording DB 16; a fluctuation rate calculation unit 13 that calculates the fluctuation rate between the reference value and the daily stock price stored in the recording DB and records this as a daily fluctuation rate in a storage DB 17; and a trend analysis unit 14 that analyzes the trend of the company's stock price based on the daily fluctuation rate recorded in the storage DB. The trend analysis unit uses the daily fluctuation rate recorded in the storage DB to perform an enthalpy transformation as a linear function of the daily fluctuation rate value on an arbitrarily selected day during the specified period and the daily fluctuation rate value on the current day, thereby showing the trend of the company's stock price as a line.

Owner:FUKUSHIMA SPRING CO LTD
Stock price prediction method based on improved VMD and multiband fusion
The invention discloses a stock price prediction method based on improved VMD and multiband fusion, and relates to the technical field of stock price prediction. Aiming at the problems that multi-scale decomposition of a financial sequence is easy to generate modal aliasing and an existing model is difficult to differentially capture multiband characteristics, the method comprises the following steps: firstly, introducing adaptive orthogonal penalty into a frequency domain functional of variational modal decomposition to realize anti-aliasing decomposition of an original sequence; secondly, frequency bands are divided according to the center frequency, and a differentiation prediction model is constructed according to the fluctuation rule of each frequency band; then, the time-varying contribution weight of each frequency band is calculated by using an attention mechanism, and dynamic weighted fusion is carried out; and finally, constructing a residual error compensation model to correct the deviation, and reconstructing to obtain a final predicted value. Compared with the prior art, the method has the advantages that the modal aliasing problem in traditional decomposition is effectively inhibited, fine modeling and dynamic integration of different frequency characteristics are realized, and the prediction precision and robustness of the model in a complex market environment are improved.

Owner:CHANGCHUN UNIV OF TECH
Stock price prediction method based on deep decomposition autocorrelation model
The invention discloses a stock price prediction method based on a deep decomposition autocorrelation model, and relates to the technical field of financial time series prediction, and the method comprises the steps: S1, data acquisition and preprocessing, S2, model architecture design, S3, model training and parameter configuration, S4, prediction generation and post-processing, and S5, deployment and application. According to the invention, a trend period characteristic decomposition module is introduced, the model can display long-term trend and short-term fluctuation in a separation time sequence, complex dynamic characteristics of a stock market are effectively captured, the prediction precision is improved, a trend period progressive decomposition mechanism in a decoder avoids information loss by refining characteristic components layer by layer, and the prediction precision is improved. The adaptive capacity to non-periodic data is enhanced, the long-term prediction result is more stable and reliable, an autocorrelation mechanism is adopted to replace a traditional attention mechanism, the sequence periodic dependence is efficiently captured through fast Fourier transform, the calculation complexity is reduced, and the training and reasoning efficiency of the model is improved.

Owner:YUNNAN UNIV
Stock price prediction method based on emotion data
PendingCN119130516AAddressing Neglected IssuesFinanceCommerceStock price forecastingFinancial transaction
The invention discloses a stock price prediction method based on emotion data. The method comprises the steps of obtaining stock text evaluation data; extracting comment characterization data from the stock text evaluation data, and constructing emotion data through the comment characterization data; building a stock price prediction model based on the emotion data, inputting the stock text evaluation data belonging to the same plate into the stock price prediction model for pre-training, and obtaining a plate sharing model; inputting the stock text evaluation data into the section sharing model for formal training; and inputting the latest stock text evaluation data into the stock price prediction model, and predicting the stock price trend of the next transaction cycle. According to the invention, the rising and falling trend of the stock price is predicted by mining the emotion text, and a new thought is provided for the development and application of a subsequent stock price prediction model.

Owner:TONGJI UNIV
Stock price prediction method, system and medium for fusing text multi-theme information
ActiveCN110363568BEfficient integrationMarket predictionsFinanceStock price forecastingPrice prediction
The present invention provides a stock price prediction method, system and medium that integrate text multi-theme information, including: a data preprocessing step: acquiring text data and stock data, preprocessing the acquired text data and stock data, and obtaining the preprocessed Post-data; model training step: according to the obtained pre-processed data, the stock price prediction model is trained to obtain the trained model. The present invention uses a multi-head attention mechanism to map text vectors to different semantic spaces, then extracts topic information, and finally fuses different topic information with different attention weights skillfully. In addition, the present invention also utilizes the encoder-decoder framework to effectively integrate text information and stock price information into a unified framework, and can dynamically adjust the influence of different time nodes on stock price prediction.


Owner:SHANGHAI JIAOTONG UNIV
Convolution gating circulation unit stock prediction method based on limit gradient lifting feature selection and secondary decomposition
The invention discloses a convolution gating cycle unit stock prediction method based on limit gradient lifting feature selection and secondary decomposition. The method comprises the following steps: acquiring historical market data of an A stock; preprocessing the A stock data; secondary decomposition is carried out on the A-strand time sequence data through EMD and VMD; EMD decomposition is carried out on the original time sequence data, and then secondary decomposition is carried out on the high-frequency IMF through the VMD; phase space reconstruction: converting the one-dimensional time sequence data into a two-dimensional phase space; performing feature selection by using a limit gradient lifting method; constructing a convolutional gating cycle unit model framework: extracting depth features by using a convolutional layer, and performing data prediction by using two GRU layers; using a genetic algorithm to optimize the parameters of the convolution gating cycle unit; predicting the decomposed IMF by using a gating cycle unit model with optimal parameters; and calculating a model error: evaluating the model through indexes such as a mean square error, a mean absolute error, a root-mean-square error and a mean relative error. The method can improve the accuracy of stock price prediction.

Owner:LIAONING UNIVERSITY
A forecasting method of future stock price based on FP-growth algorithm
The invention discloses a method based on FP-Growth algorithm for future stock price forecasting, includes such steps as S101, extracting characteristic factors of single stock: pre-collecting price-earnings ratio, profit fundamental factor, average line and volatility technical factor, converting numerical data into classified data, and determining characteristic factors of single stock as basiccharacteristics of stock price. S103, determining a single target factor: extracting a characteristic factor time point of a single stock in the step S101 in advance, and processing data of a component category with stock price characteristic numerical data three months after the time point to determine a single target factor; S105, determining a single template: combining the characteristic factors of the individual stocks in step S101 and the target factors in step S103, and determining a single sample. The invention has the characteristics of intuitionistic and explainable, and the operatiom speed of the FP-growth algorithm is quite fast; and compared with the common regression and classification algorithm, the FP-growth algorithm has more efficient advantages.

Owner:安徽磐众信息科技有限公司