

Patents
Literature
457 results about "Credit card" patented technology
Efficacy Topic
Property
Owner
Technical Advancement
Application Domain
Technology Topic
Technology Field Word
Patent Country/Region
Patent Type
Patent Status
Application Year
Inventor
Proactive benefit scan
An example operation may include one or more of receiving an identifier of a product from a digital wallet on a user device, identifying one or more payment cards stored within the digital wallet on the user device, determining benefits that will be obtained by using each of the one or more payment cards to purchase the product via execution of an LLM on the identifier of the product and a corpus of credit card documents, and displaying a chat message within a chat window on the user device with a description of the determined benefits that will be obtained.

Owner:THE TORONTO DOMINION BANK
GenAI LETTER OF CONFIRMATION OF BENEFITS
An example operation may include one or more of storing a data store of credit card documentation, conversing with a user via a chatbot within a chat window of a software application, wherein the conversing comprises receiving natural language inputs with requests for information about a payment card, identifying a benefit obtained by the user based on the conversation, executing a large language model (LLM) on the identified benefit and the data store of the credit card documentation to generate a letter of confirmation, and generating an electronic message with the letter of confirmation attached, and transmitting the electronic message to a user device.

Owner:THE TORONTO DOMINION BANK
Utilizing machine learning models to generate fraud predictions for card-not-present network transactions
The present disclosure relates to systems, non-transitory computer-readable media, and methods for utilizing a card-not-present machine learning model to generate a fraud prediction for a network transaction where a credit card used for the transaction is not present. In particular, in one or more embodiments, the disclosed systems identify features associated with the network transaction and generate, utilizing the card-not-present machine learning model, a fraud prediction based on the identified features. The disclosed systems can also apply transaction logic based on the fraud prediction to process the network transaction by performing an authorizing, declining, or other action with regard to the network transaction.

Owner:CHIME FINANCIAL INC
System of security that prevents abuse of identity data in global commerce via mobile wireless authorizations
ActiveUS12423709B2User identity/authority verificationMessaging/mailboxes/announcementsCredit cardComputer network
A system of security that prevents misuse of identity data of an identity data owner in an identity data driven transaction in a global commerce network, that has in the system, a transaction processing entity that after it receives a identity data driven transaction from a transaction initiating entity, puts on hold the processing of the transaction for a period of time and via the identity data owner's wireless mobile communication device, contacts the identity data owner for authorization of the transaction before the transaction processing is completed. The system of security for identity data may be used in the identity data driven transaction is one from a group of (i) credit card payment, (ii) bank account payment, (iii) release of credit profile, (iv) release of financial data, and (v) release of medical data.

Owner:SINGHAL TARA CHAND
Math based currency point of sale systems and methods
Systems, methods, and computer-readable storage media utilized for processing open loop math based currency (“MBC”) credit card transactions at a financial institution. One method includes receiving, via an open loop processing network, a request for an MBC transaction and generating a first code uniquely identifying the MBC transaction. The method further includes transmitting, via the open loop processing network, the first code to the customer computer device and receiving, from an acquirer / processor computer system via the open loop processing network, a second code including the first code and a public and private key pair. The method further includes determining that the public key is registered and updating a first entry of an overlay ledger and a second entry of the overlay ledger. The method further includes transmitting, via the open loop processing network, a credit guarantee and transmitting, via the open loop processing network, a receipt of the MBC transaction.

Owner:WELLS FARGO BANK NA
Application program, payment system, and terminal device control method
To provide an application program or the like capable of combining points issued to a user with electronic money usable in electronic settlement to pay the bill on a credit card, thereby improving convenience for the user. [Solution] An application program that causes a terminal device capable of communicating via a network with a credit card company server managed by a credit card company to display the credit card billing amount on a display unit of the terminal device, obtain the amount of electronic money that can be used for electronic payment to apply to the billing amount, obtain the number of points awarded to the user in connection with the user's purchase of a product to apply to the billing amount, and send an application instruction to the credit card company server instructing the amount of electronic money and the number of points to be combined and applied to the billing amount.

Owner:PAYPAY CO LTD
Credit text analysis method, credit object auditing method and credit object auditing device
PendingCN114386430AReduce labor costsImprove efficiencyFinanceSemantic analysisEngineeringData mining
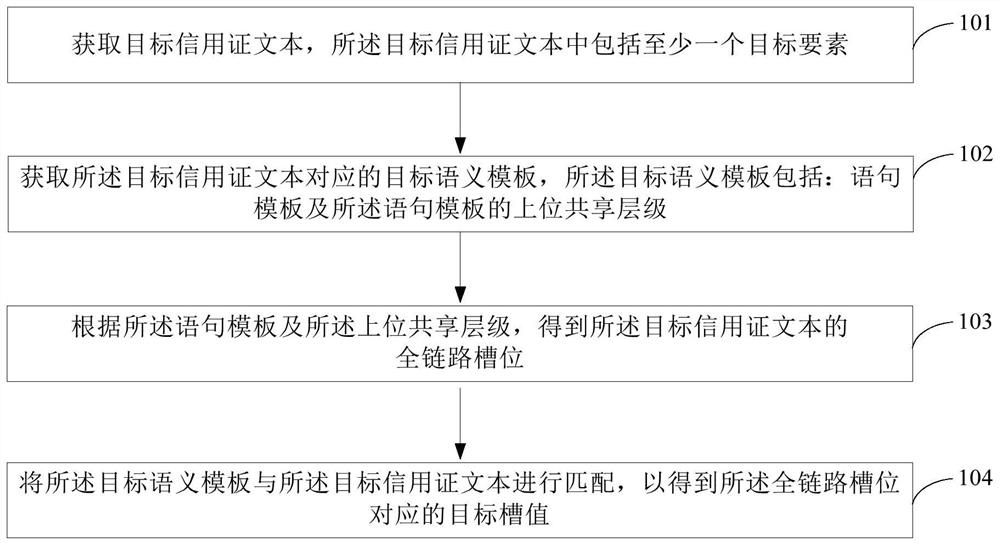
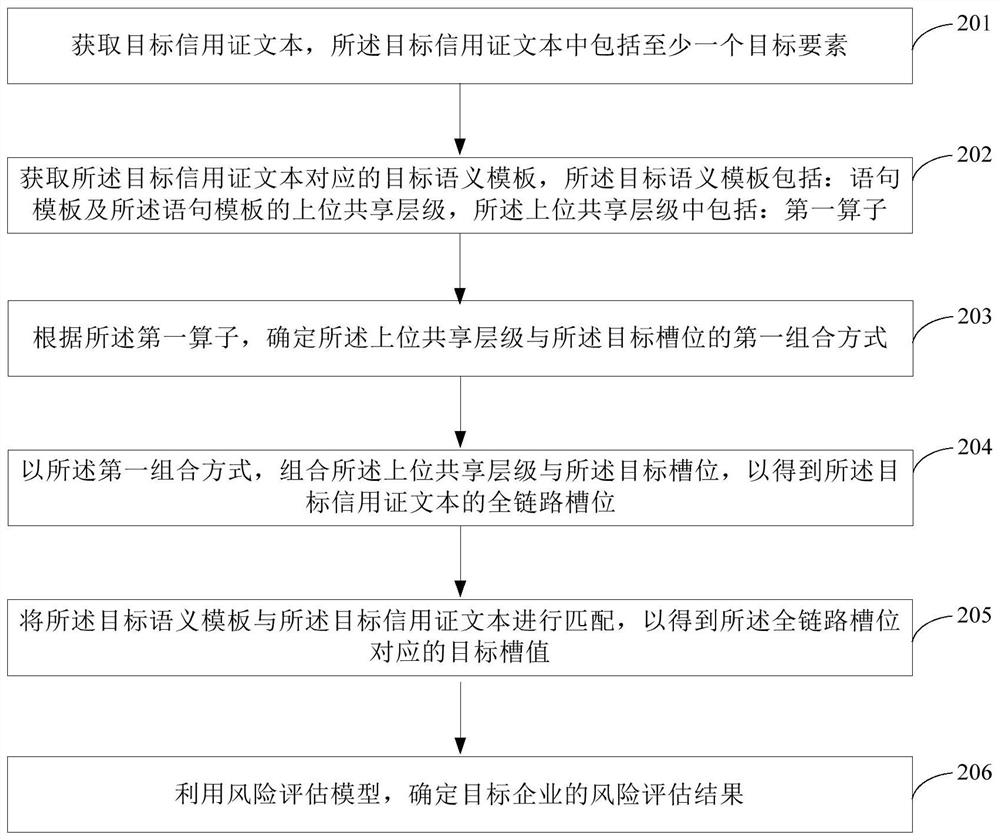
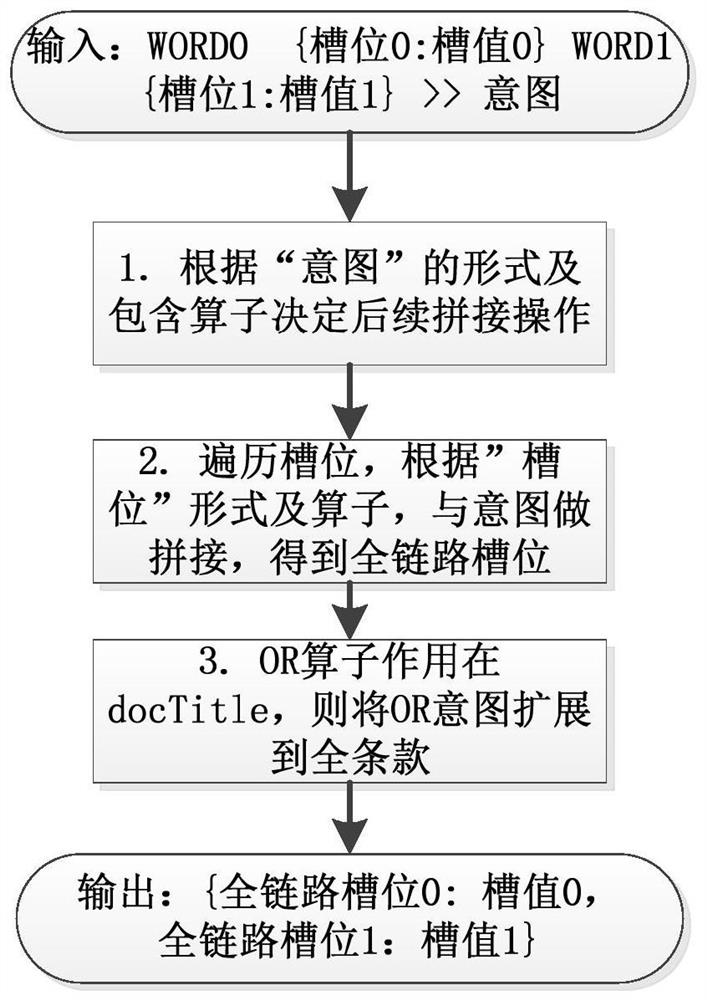
The invention discloses a credit text analysis method and a credit object auditing method and device, and relates to the technical field of knowledge maps. A specific embodiment of the method comprises the steps of obtaining a target credit card text, wherein the target credit card text comprises at least one target element; a target semantic template corresponding to the target credit document text is obtained, the target semantic template comprises a statement template and an upper sharing hierarchy of the statement template, the statement template comprises at least one target slot position, and the target slot position corresponds to the target element; obtaining a full-link slot position of the target credit card text according to the statement template and the upper sharing hierarchy; and matching the target semantic template with the target credit text to obtain a target slot value corresponding to the full-link slot position. According to the implementation mode, the slot position and the slot value corresponding to the element in the credit card can be automatically obtained, and the related content in the credit card text can be analyzed.
Owner:CHINA CONSTRUCTION BANK
Systems and methods of encoding BNPL transactions for terminal devices
Systems, methods, and computer readable media may facilitate buy-now-pay-later (BNPL) transactions at brick-and-mortar locations of merchants that otherwise lack an ability to interface with financial institutions (FIs) that finance BNPL transactions. Likewise, the system may be used to conduct BNPL transactions for merchants that lack an electronic commerce presence. For example, a payment network used to process payment cards such as credit cards may be leveraged to communicate with user devices, merchant point of sale (POS) terminals, and BNPL servers operated by FIs to mediate BNPL transactions. In particular, the payment network may receive, from merchants, a list of items that are eligible for BNPL transactions and installment offers from FIs to pay for BNPL transactions. The payment network may match eligible items with installment offers, select the best installment offers for the buyer, and mediate exchanges between the parties to settle payments for the BNPL transaction.

Owner:MASTERCARD INT INC
Card holder for holding at least one card
A card holder for holding at least one card corresponding to a credit card format includes a receiving device with a receiving opening and interior. The at least one card can be received in the interior through the receiving opening. The cardholder further includes an ejector arranged in the interior and rotatable about a shaft. An actuator is connected to the ejector and is rotatable with the ejector about the shaft. The at least one card can be moved out of the interior through the receiving opening in response to an actuating movement of the actuator relative to the receiving device from an initial position to an output position.

Owner:TRAVANDO GMBH
Information processing terminal, information management device, display control method, information management method, and program
To enable the user to understand the compensation content even if they forget the existence of the incidental insurance of the credit card. 【Solution means】The first acquisition unit 211 acquires first information regarding the incidental insurance of the credit card associated with the user U of the electronic payment based on an operation on the payment application regarding the electronic payment. The display control unit 212 displays a display based on the first information on the screen of the payment application. The operation is an operation on the insurance icon C1 for displaying information regarding the insurance subscribed by the user U using the account of the electronic payment.

Owner:NTT DOCOMO INC
Credit card propaganda image-text generation method and device
The invention discloses a credit card propaganda image-text generation method and device, and relates to the technical field of finance, and the method comprises the steps: screening a plurality of historical credit card propaganda prompt words according to the latest supervision requirements, and obtaining a plurality of compliant credit card propaganda prompt words; obtaining information of a plurality of credit card products, and determining a propaganda prompt word corresponding to each credit card product; inputting the basic information of the user into a credit card recommendation model, and outputting target credit card product information suitable for the user; inputting the character information of the target credit card product and the propaganda prompt word corresponding to the target credit card product into a financial document model, and outputting credit card propaganda document information; and inputting the basic information of the user, the target credit card product information and the credit card propaganda copywriting information into the text graph model to obtain a credit card propaganda image-text. According to the invention, high-quality and compliant credit card propaganda images and texts can be generated, and the efficiency of generating the credit card propaganda images and texts is improved.

Owner:CHINA CONSTRUCTION BANK +1
Labor management server, credit card management server, labor management method, credit card management method, and program
To provide a labor management server, a labor management method, a program, etc., which can easily register a salary receiving account and improve convenience for users. [Solution] A labor management server capable of communicating with a terminal device operated by a company's employees and an information processing device that provides a service, the labor management server comprising: a generation unit that generates app launch information including employee identification information for identifying the employee, server identification information for identifying the labor management server, and a link for launching an app for using the service; a transmission unit that transmits the app launch information to the terminal device; a receiving unit that receives from the information processing device an account linking result between the labor management server and the information processing device; and an account management unit that manages the employee's account information for the service included in the account linking result as a transfer account for the employee's salary.

Owner:PAYPAY CO LTD
Systems and methods for end-to-end consumer lending and financing solutions for choosing a credit card
Embodiments of the systems and methods of using the same are configured to provide a financial solution product for customers seeking financing and advice for debt consolidation, home improvement, financing for school loans, finding the right credit card, and financing collateral. The systems and methods provide a means to dynamically calculate multiple financial solution products and present them to a user.

Owner:PNC FINANCIAL SERVICES GROUP INC
Smart system for combating nicotine dependence
The invention relates to the field of smokers' requisites, and more particularly to electronic cigarettes, and can be used as a hardware and software system for helping to combat nicotine dependence. The aim of the invention is to improve and to increase the efficiency, in the proposed smart system for combating nicotine dependence, of a system for providing feedback to a user, specifically in the form of an indicator, and sending notifications and warnings and motivating the user by means of the electronic cigarette itself or by a software application. This aim is achieved in that in the claimed smart system for combating nicotine dependence, feedback is provided to the user by indicator light and vibratory modules, as well as by a piezoelectric noise emitter, which are built directly into an electronic cigarette, as well as by notifications and push notifications sent by a software application to a smartphone, tablet, laptop, computer, smart watch or bracelet, or chatbot messages, and by the possibility of deducting money from the user's credit card.

Owner:ALFABET LABS DMCC
Information processing device, information processing method, and information processing program
To allow a contractor of a credit card to smoothly register use of a service using a family card which can be issued to a family member, the service being available under the condition of using a credit card.SOLUTION: An information processing device includes a reception unit 131, a registration unit 132, an identification processing unit 133, and a use registration processing unit 134. The identification processing unit 133 performs, in a procedure for registering use of a predetermined service by a second user, identification processing using a telephone number associated with a predetermined identification number which is preliminarily assigned to a family card to identify the family card. If the identification processing for the second user has succeeded, the use registration processing unit 134 registers, in a storage unit, information indicating that the use registration of the predetermined service is complete.SELECTED DRAWING: Figure 5

Owner:PAYPAY CO LTD
Systems and methods for physical math based currency (MBC) credit cards
Embodiments include a method of performing math based currency (“MBC”) exchanges. One method includes receiving an exchange request from a merchant point-of-sale (POS) system and determining a merchant POS system accepts MBC payments. The method further includes exchanging, on a published blockchain, an amount of MBC equal to an amount to an MBC account of the merchant POS system and updating a pooled account database. The method further includes updating an overlay ledger to modify an MBC balance of the MBC credit card account held by the customer and broadcasting the exchange to a plurality of MBC verification nodes for verification.

Owner:WELLS FARGO BANK NA
Method and managing module for managing an escrow payment service
InactiveUS20250078045A1Cryptography processingBuying/selling/leasing transactionsCredit cardUser device
A method and a managing module “MM” (110) for managing an escrow payment service for purchases in a store of a vendor. The MM (110) receives purchase information comprising an identity of the vendor, an identity of a customer, a price, an offer specification and a condition. The MM (110) stores the identity of the vendor, the identity of the customer, the price and the offer specification. The MM (110) stores the respective number of the vendor and the customer and the condition in a smart contract on a blockchain (130). The MM (110) sends a request for acceptance of the smart contract and receives a response for accepting the smart contract. The MM (110) sets a state of the smart contract to accepted. The MM (110) sends a transaction request. The MM (110) stores the transaction identity in the smart contract. The MM (110) receives a transaction response indicating that the temporary credit card holds the funds corresponding to the price. The MM (110) stores, in the smart contract, an indication of that the transaction is completed. The MM (110) sends, to the server (111) and the user device (120), a notification confirming successful payment and login details for access to list of transactions of the smart contracts smart contract. The MM (110) checks the conditions of the smart contract to obtain an answer indicating fulfilment or non-fulfilment of the conditions. The MM (110) sets the state of the smart contract to completed or rejected. A corresponding computer program (403) and a computer program carrier (405) are also disclosed.

Owner:BCV I ROBERTSFORS AB
J-credit support device, j-credit support method and program
To address such a problem that conventionally, it is not possible to appropriately support J-Credit applications.SOLUTION: A J-Credit support device 1 includes an image acquisition unit 131 for acquiring a captured image including one or more inspection areas, a first determination unit 132 using a partial image of the inspection area to determine whether or not each of the one or more inspection areas satisfies a forest condition for determining whether or not it is a forest area and acquiring a first determination result, and a determination result output unit 141 for outputting the first determination result, the J-Credit support device thus appropriately supporting the J-Credit applications.SELECTED DRAWING: Figure 1

Owner:MITSUI & CO LTD
Integrated global tokenization system
An integrated selling system platform includes a point-of-sale application and middleware to perform global tokenization orchestration, that in combination, provide credit card reading device agnostic global token and provisioning operations. The middleware includes communication interfaces, each of which corresponds to a particular communication protocol. The middleware receives a token create request from the point of sale application and directly communicates, via one of the communication protocols, to a point-of-interaction payment device, to receive and securely encrypt the credit card number, then transmit that information to a hosted network token provisioning system to request a network token. Upon receiving the network token, the middleware communicates directly, via one or more protocols, to a global merchant tokenization host, to create a merchant specific token, to be returned by the middleware back to the point-of-sale client to use as a card-on-file payment method.

Owner:FREEDOMPAY INC
Games, prizes, and entertainment for powered cards and devices
Advanced payment applications are provided to improve the functionality of cards and devices. For example, a user interface may be placed on a card (e.g., a physical button) or a telephonic device (e.g., a virtual button on a capacitive touch screen). Manual input provided to this user interface may, for example, cause a purchase to be paid by credit and points may be earned for the purchase. A different manual input may, for example, cause a purchase to be paid by credit and points not be earned for the purchase in exchange for one or more chances to win a prize in a random lottery. An instant winner functionality may be provided on a card. For example, a card may randomly become an instant winner based on, for example, time and / or use.

Owner:DYNAMICS INC
Preparation method of wear-resistant and scratch-resistant water-based ink
The invention relates to the field of ink, in particular to a preparation method of wear-resistant and scratch-resistant water-based ink. The water-based ink is prepared from the following components in parts by weight: 30 to 50 parts of self-crosslinking modified acrylic emulsion, 5 to 15 parts of modified calcium hexaboride, 5 to 20 parts of toner, 0.8 to 1.6 parts of dispersing agent, 0.5 to 2 parts of wetting leveling agent, 0.1 to 0.5 part of defoaming agent, 0.5 to 2 parts of pH regulator and 10 to 30 parts of deionized water. Through the synergistic effect of the self-crosslinking modified acrylic emulsion and the surface functionalization modified calcium hexaboride, the defect that hardness and toughness of traditional water-based ink are difficult to consider at the same time is overcome. The obtained ink film has extremely high hardness and adhesive force, also has excellent wear resistance which is far better than that of traditional water-based ink, and can meet the requirements of high-end electronic product shells, durable labels, credit cards and other application scenes with extremely harsh requirements for surface durability.

Owner:DONGGUAN HUAHONG SCREEN PRINTING MATERIALS CO LTD
Portable personal toiletry article holder
A portable personal toiletry article holder in the form of a one-piece flexible card includes one or more openings, where each of the one or more openings are designed for temporary support of a personal toiletry article. The one-piece flexible card includes space for displaying at least one of instructions for use of the portable personal toiletry article holder or marketing information for a business. The portable personal toiletry article holder can have multi-purpose uses such as use as an electronic key, as personal identification card, as a credit or bank card, and as a business card.

Owner:SWEENEY MARK MORGAN
User abnormal transaction probability identification method based on block chain, electronic equipment and storage medium
The embodiment of the invention provides a block chain-based user abnormal transaction probability identification method, electronic equipment and a storage medium. The method comprises the following steps: performing iterative training on an initial transaction recognition model through a locally stored user transaction data set to obtain a first transaction recognition model corresponding to the trained initial transaction recognition model; uploading a first training parameter carried by the first transaction identification model to cloud service equipment through encryption transmission; under the condition that an updating instruction fed back by the cloud service equipment is received, downloading a second training parameter from the cloud service equipment; and adjusting the first transaction identification model according to the second training parameter to obtain a target transaction identification model, and identifying locally updated credit card transaction data of the to-be-identified user through the target identification model to obtain an abnormal transaction probability corresponding to the to-be-identified user.

Owner:AGRICULTURAL BANK OF CHINA
Method for constructing retail credit risk prediction model and credit card service Scorealpha model
The invention relates to a credit card service Scorealpha model and a method for predicting retail credit risks by using the model, and the method comprises the steps: a data collection step: obtaining retail credit prediction data of a to-be-predicted sample; a step of classifying the to-be-predicted samples, wherein the to-be-predicted samples are classified based on a decision tree method so as to determine a sub-model used for calculating the credit default probability; and a credit default probability calculation step of substituting the retail credit prediction data into the credit default probability sub-model to calculate the credit default probability of the to-be-predicted sample. The invention also relates to a method for constructing the retail credit risk prediction model. The method comprises a data acquisition step, a data derivation step, a feature preliminary screening step, a preliminary screening data conversion step, a feature fine screening step and a credit default probability modeling step.


Owner:CCB FINTECH CO LTD
Accounting management method and device based on transaction sub-account, and related equipment
The invention provides an accounting management method and device based on a transaction sub-account and related equipment, and the method comprises the steps: classifying the amount statistical value fields on a management account of a credit card, and obtaining a corresponding classification result; identifying a transaction sub-account generated in the credit card transaction process; and performing parameterization configuration on a plurality of specified fields of the transaction sub-accounts according to a classification result so as to map the transaction sub-accounts back to the management account. According to the scheme, the amount statistical value fields on the management account are classified, parameterization configuration is performed on the plurality of specified fields of the transaction sub-accounts according to the classification result, so that the transaction sub-accounts are mapped back to the management account, mapping of the original management account is realized on the basis of newly increasing the dimension of the transaction sub-accounts, the accounting framework is optimized, and the transaction efficiency is improved. And therefore, detailed, accurate and multivariate accounting management can be realized.

Owner:AGRICULTURAL BANK OF CHINA
Credit card risk prevention and control method and system based on Stacking ensemble learning
InactiveCN119648374Areduce trainingshorten the timeFinanceEnsemble learningCredit cardRisk prevention
The invention belongs to the field of social risk prevention and control, and discloses a credit card risk prevention and control method and system based on Stacking ensemble learning, and the method comprises the steps: preprocessing a data set, extracting key features, and employing a resampling technology to balance positive and negative examples; constructing a shallow feature rule by means of a diversified machine learning method, and establishing a deep neural rule by using deep learning technologies such as a multi-layer perceptron; based on a Stacking ensemble learning method, a feature rule and a neural rule are fused. According to the invention, the risk can be identified and predicted more accurately, so that the accuracy and timeliness of early warning are improved; through fusion optimization of multiple rules, the problems of ambiguity, conflict, non-uniformity and the like in current social governance and risk prevention and control rules are solved.

Owner:BEIJING INST OF TECH
Information processing device, information processing system, information processing method and information processing program
To block unnecessary card insertion upon card settlement to guide a user to touch settlement.SOLUTION: An information processing device 13 includes a communication unit 131 that performs radio communication with a credit card 11, and a control unit 132 that determines whether or not settlement of the credit card 11 by radio communication is possible to control a notification that the settlement by radio communication is possible, according to a determination result.SELECTED DRAWING: Figure 2

Owner:OKI ELECTRIC INDUSTRY CO LTD
Modifying signal associations in complex computing networks
Described are methods and systems for registering consumers with merchant loyalty or other merchant programs by using a credit card or other form of payment to register the consumer, and thereafter automatically recognizing the consumer as a member in the program based on subsequent purchases made using the form of payment. This disclosure is also directed to an apparatus and related methods for modifying a temporal signal association in a complex computing network such that a future computing operation is executed based on the modified signal association.

Owner:MANKOFF JEFFREY W
Credit card collection method, device and equipment, medium and product
The invention discloses a credit card collection method and device, equipment, a medium and a product, and relates to the technical field of artificial intelligence, and the method comprises the steps: determining a target user having an association relationship with a to-be-collected user, carrying out the feature splicing according to a target user feature vector of the target user and a to-be-collected user feature vector of the to-be-collected user, and obtaining a to-be-collected user feature vector of the to-be-collected user; determining a user feature optimization vector; determining a verbal skill vector optimization matrix according to the verbal skill vector matrix of the candidate collection verbal skill and the word vector of the candidate collection word, and determining a channel feature optimization vector according to the channel feature vector of the candidate collection channel; and according to the user feature optimization vector, the verbal skill vector optimization matrix and the channel feature optimization vector, determining a target collection verbal skill and a target collection channel for collecting the to-be-collected user. The effect of intelligently and automatically selecting the collection channel and the collection verbal skill which are most suitable for the to-be-collected user is achieved, the cost of human input is reduced, and the efficiency and the success rate of credit card collection are improved.

Owner:INDUSTRIAL AND COMMERCIAL BANK OF CHINA
Order payment graphical user interface for electronic device
1.The name of the design product: order payment graphical user interface of electronic device. 2.The use of the design product: an electronic device. 3.The design points of the design product: the content of the graphical user interface. 4.The picture or photo that best shows the design points: design 1 front view. 5.Specify design 1 as the basic design. 6.The use of the graphical user interface: for order payment; clicking the credit card payment button of design 1 front view can jump to design 1 interface change state figure 1, clicking the confirmation button of design 1 interface change state figure 1 can jump to design 1 interface change state figure 2, in design 1 interface change state figure 2, after completing payment through the device, it can jump to design 1 interface change state figure 3, in design 1 interface change state figure 3, when the order enters the queue, it can jump to design 1 interface change state figure 4; clicking the cash payment button of design 2 front view can jump to design 2 interface change state figure 1, clicking the confirmation button of design 2 interface change state figure 1 can jump to design 2 interface change state figure 2, in design 2 interface change state figure 2, after completing payment through the device, it can jump to design 2 interface change state figure 3, in design 2 interface change state figure 3, when the order enters the queue, it can jump to design 2 interface change state figure 4; clicking the cash payment button of design 3 front view can jump to design 3 interface change state figure 1, clicking the confirmation button of design 3 interface change state figure 1 can jump to design 3 interface change state figure 2, clicking the credit card payment button of design 3 interface change state figure 2 can jump to design 3 interface change state figure 3, clicking the confirmation button of design 3 interface change state figure 3 can jump to design 3 interface change state figure 4, in design 3 interface change state figure 4, after completing payment through the device, it can jump to design 3 interface change state figure 5, in design 3 interface change state figure 5, when the order enters the queue, it can jump to design 3 interface change state figure 6.

Owner:广州逸仙科技有限公司