
Patents
Literature
50results about How to "Iteration is simple" patented technology
Efficacy Topic
Property
Owner
Technical Advancement
Application Domain
Technology Topic
Technology Field Word
Patent Country/Region
Patent Type
Patent Status
Application Year
Inventor
Face microexpression recognition method
InactiveCN104298981AOutstanding FeaturesHighlight significant progressAcquiring/recognising facial featuresGraphicsPattern recognition
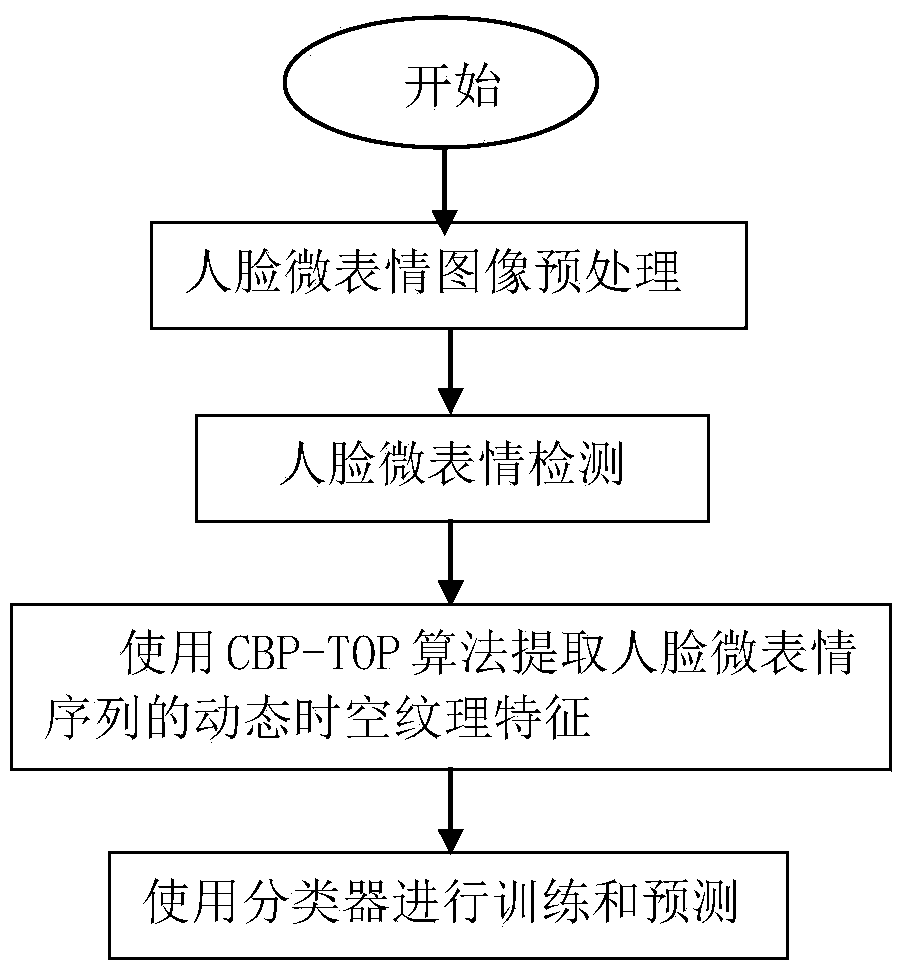
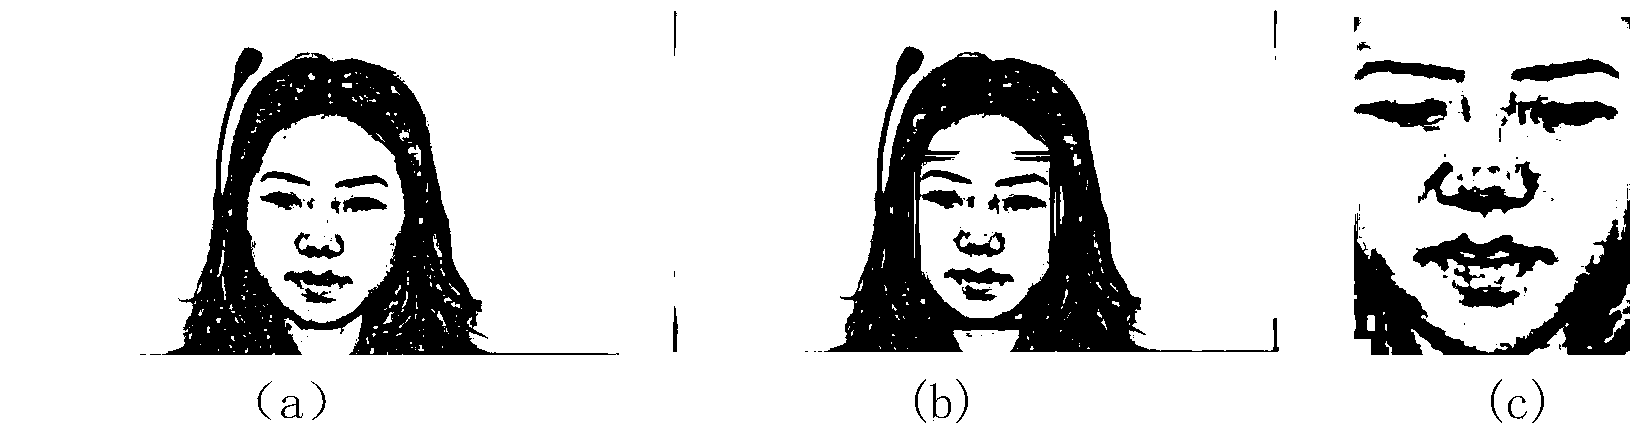
The invention discloses a face microexpression recognition method and relates to a method for recognizing graphs with electronic equipment. The method comprises the steps that after a face microexpression image sequence is preprocessed, the Birnbaum-Saunders distribution curve is used for building a regression model, then the CBP-TOP algorithm is used for extracting dynamic space-time texture features of the face microexpression sequence, and finally a classier is used for training and prediction. The defect that an existing face microexpression recognition method is sensitive to small features such as bright points, edges and white noise of a face microexpression image, thereby being low in recognition performance is overcome.
Owner:HEBEI UNIV OF TECH
Laser photography measuring system and camera calibration method
ActiveCN105486289ASimple structureEasy to operatePicture taking arrangementsElectricityLaser transmitter
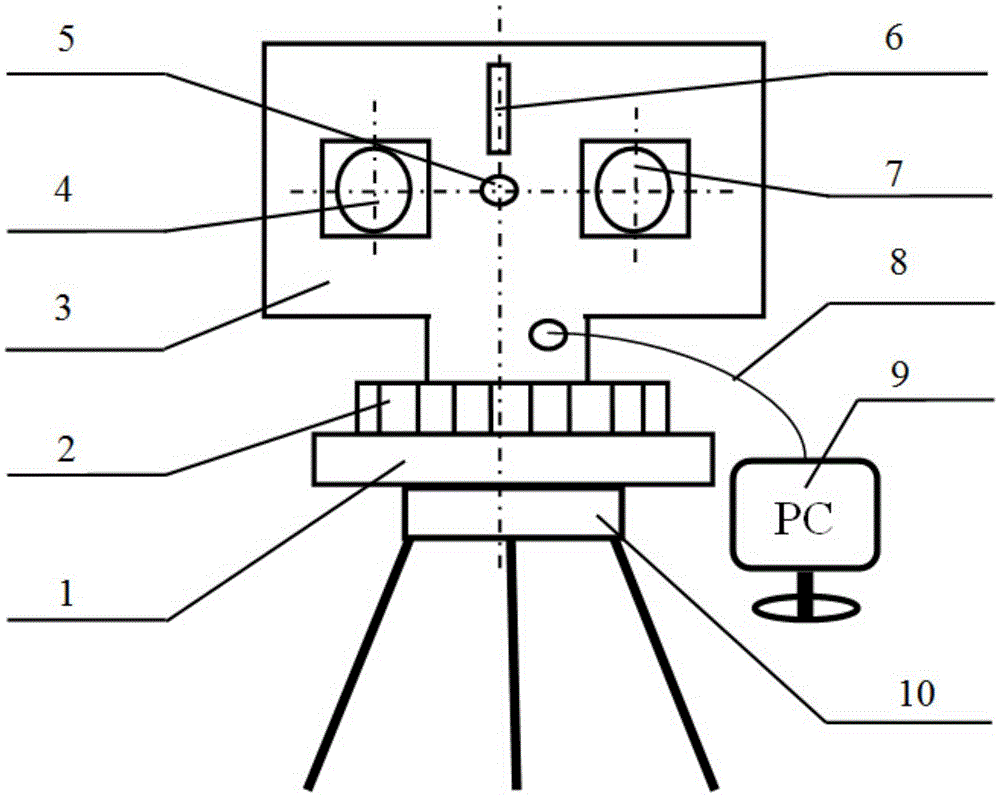
The invention relates to a laser photography measuring system and a camera calibration method. The system comprises a measuring device and a calibration device. The measuring device comprises a base, a support and a computer. The support is rotationally arranged on the base, the support is provided with cameras, a laser distance measuring device and a linear laser emitter, the laser distance measuring device and the linear laser emitter are located on the same vertical line, the two cameras are symmetrically arranged on the two sides of the laser distance measuring device, and the computer is electrically connected with the cameras, the laser distance measuring device and the linear laser emitter. The calibration device comprises three object space plates and evenly-distributed object space identification points. By means of the measuring device, the calibration device, the object space plates and the object space identification points, precise calibration of the cameras of the measuring system can be effectively achieved through photographing of the cameras and corresponding subsequent programmed programs. The camera calibration method is simple in step and easy to operate, and reliable bases are provided for subsequent laser photography measuring.
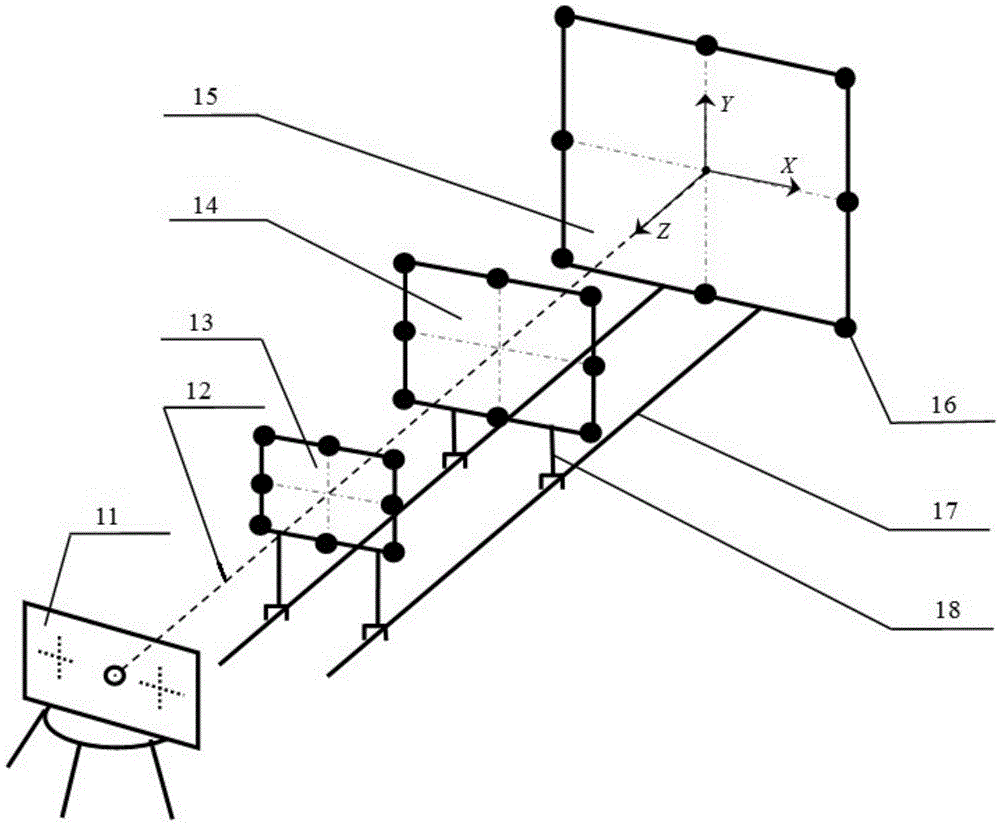
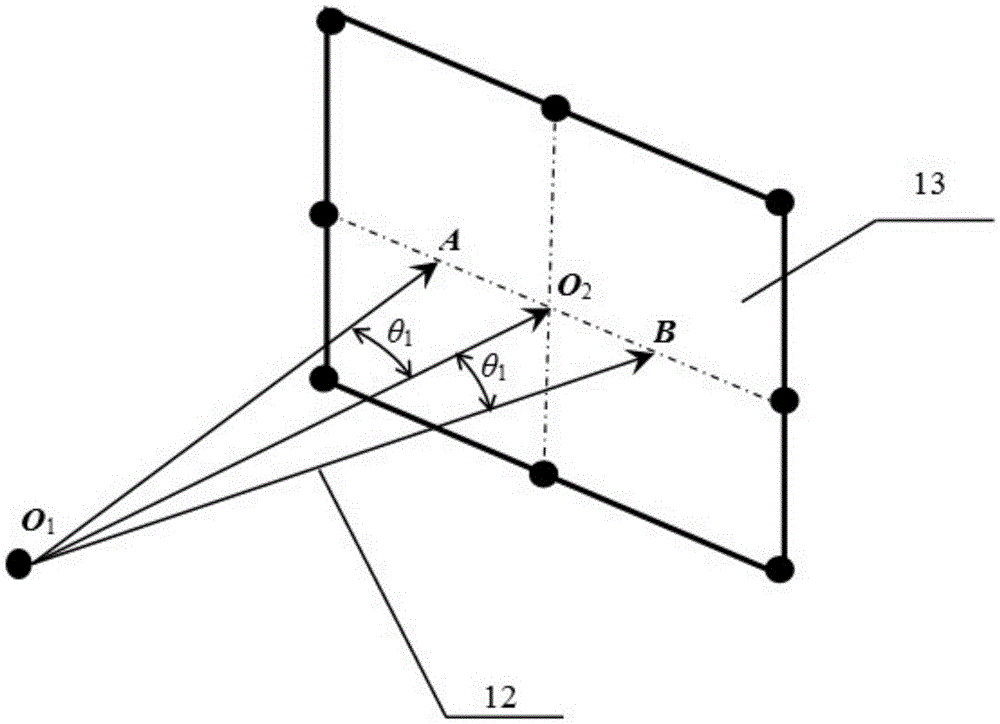
Owner:SHANDONG UNIV OF SCI & TECH
Non-parallel storage life test evaluation method based on accelerating factor feasible region selection
ActiveCN104680005AGuaranteed accuracyIteration is simpleSpecial data processing applicationsAcceleration factorAlgorithm
The invention discloses a non-parallel storage life test evaluation method based on accelerating factor feasible region selection. The method comprises the following steps: I, calculating an accelerating factor and comprehensive failure time; II, discussing an accelerating factor feasible region; III, performing parameter selection by using an optimal linear unbiased estimation method; IV, calculating the point estimation and interval estimation of logarithm reliable life. Specific to the phenomenon of missing of storage data in non-parallel storage product life estimation, storage data and test data are integrated, and calculation is performed by making full use of data on the basis that the service life follows Weibull distribution, so that the accuracy of life model parameter estimation is ensured, an algorithm has low requirement on the initial value of a parameter, the algorithm iteration is rapid and simple, and the operability is high.


Owner:BEIHANG UNIV
Method for evaluating storage life of regular sampling detection type products
ActiveCN104778354AGuaranteed accuracyIntegrity guaranteedSpecial data processing applicationsSmall sampleOperability
The invention discloses a method for evaluating the storage life of regular sampling detection type products. The method comprises the following steps of 1, correcting an upside down phenomenon in original test data by using a PAVA (Pool-Adjacent-Violators Algorithm); 2, obtaining minimum chi-square estimation of parameters of a distribution function, and calculating pearson chi-square statistics; 3, carrying out a pearson chi-square goodness-of-fit test; 4, calculating the reliable service life of the products under a preset storage condition. The method disclosed by the invention has the advantages that the accuracy and the integrality of distribution parameter estimation of the service life are ensured, the requirement of the algorithm on initial values of parameters is lower, the algorithm iteration is quick and simple, and the operability is strong; compared with MLE (Maximum Likelihood Estimation), the requirement on the sample capacity is lower, the evaluation result is more stable, and the superiority during processing small sample data of the method is expressed.


Owner:BEIHANG UNIV
Method and apparatus for peak to average power ratio reduction
ActiveCN105659547ALower levelReduce computational complexityMulti-frequency code systemsEngineeringTransmitter


Owner:GUANGDONG OPPO MOBILE TELECOMM CORP LTD
Optimization design method for high-frequency and high-voltage transformer used for electrostatic dust collection
ActiveCN106096106AImprove efficiencyIteration is simpleArtificial lifeSpecial data processing applicationsEngineeringParticle swarm algorithm
The invention discloses an optimization design method for a high-frequency and high-voltage transformer used for electrostatic dust collection. The method comprises the steps of selecting a proper magnetic core; for characteristics of a high-frequency transformer, combining a particle swarm algorithm with a genetic algorithm based on a design method for the high-frequency and high-voltage transformer; and performing optimization design on the transformer by taking a transformer turns ratio and a waveform duty ratio as optimization variables and taking output loss as an optimization target. According to the method, the genetic particle swarm algorithm is adopted, namely, a selection algorithm, a crossover operation and a mutation operation of the genetic algorithm are introduced in the particle swarm algorithm based on the particle swarm algorithm, and the algorithm is simple in iterative process and is advantageous in that the algorithm is easily understood and realized, the convergence speed is relatively high, efficiency is quite high and the like.


Owner:JIANGSU XINHUANENG ENVIRONMENTAL ENG CO LTD
Distribution network power flow calculation method of self-adaptive grid structure
ActiveCN107895953AAvoid missingAvoid calculation errorsAc networks with different sources same frequencyElectrical devicesControl area
The invention discloses a distribution network power flow calculation method of a self-adaptive grid structure. The method includes performing the power flow calculation according to a calculation mode set by a user; verifying the electrical equipment parameters and the topological connection relations required by the power flow calculation; identifying an outgoing line switch and determining a control area according to the position of an interconnection switch; determining a calculation range according to the setting of the user; forming a network topology and a sub-network unit; determiningthe network type and determining the wiring mode of the sub-network unit; self-adaptively matching the corresponding power flow algorithm according to the type of the sub-network unit; performing theout-of-limit, heavy load or network loss calculation; and performing the three-phase power flow and the three-phase imbalance statistics. According to the method, the number of the network nodes is greatly reduced, the calculation speed and efficiency are improved; the advantages of the algorithms are maximized, the stability and the convergence of calculation are ensured; the requirement of a dispatcher on the on-line power flow can be well met, and the application prospect is good.


Owner:南京海兴电网技术有限公司 +2
Multi-scale quantum harmonic oscillator optimization system and method
InactiveCN105787154AIncrease sampling densityReduce the number of sampling pointsComplex mathematical operationsComputational intelligenceQuantum harmonic oscillator
The invention relates to the field of computational intelligence, and relates to a multi-scale quantum harmonic oscillator concurrent optimization system and method. The method in the invention is composed of three embedded iteration processes: scale iteration, quantum harmonic oscillator iteration and energy level iteration. By adopting the method provided by the invention, sampling points to be compared at each time are fewer and are easier to fully iterate, so the result is accurate. According to the concurrency of the multi-scale quantum harmonic oscillator multimode optimization method, the Multi-scale quantum harmonic oscillator concurrent optimization method is proposed, and the method can be concurrently operated on a cluster. By adopting the concurrent method, the operational speed is effectively accelerated.
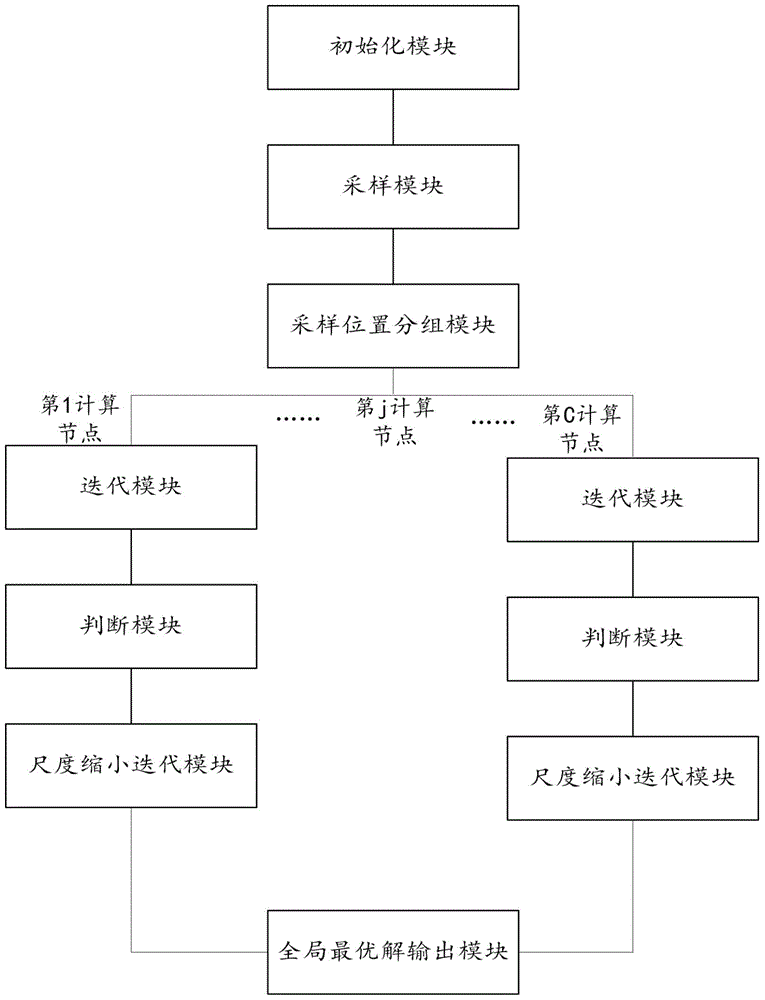
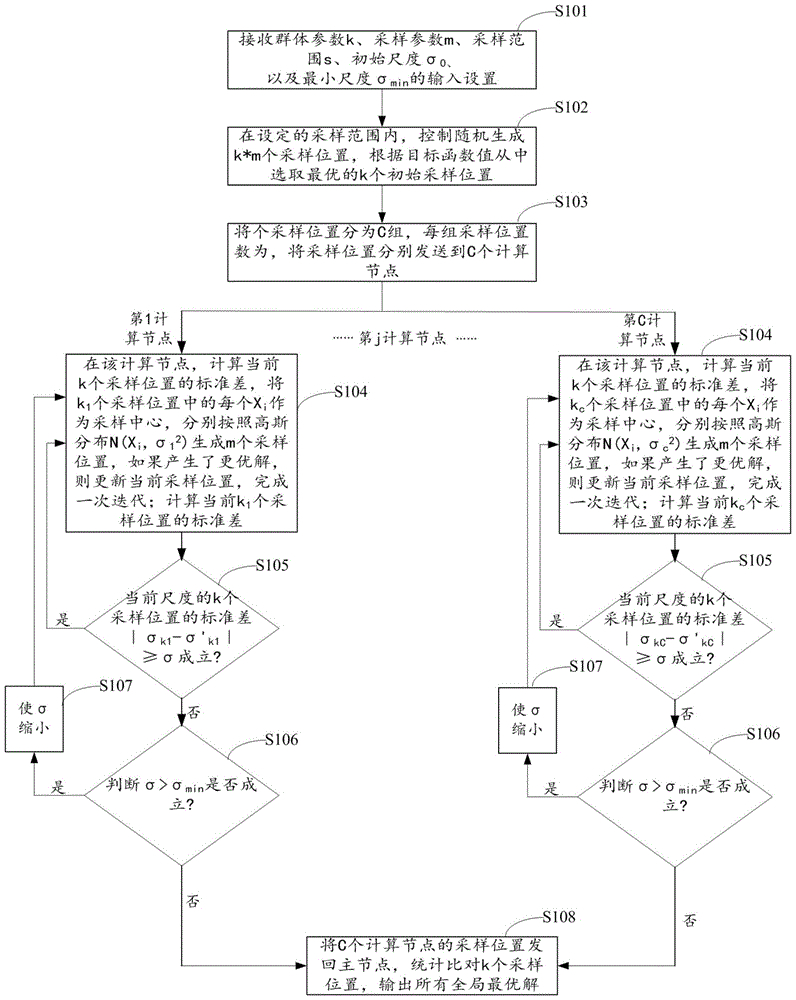
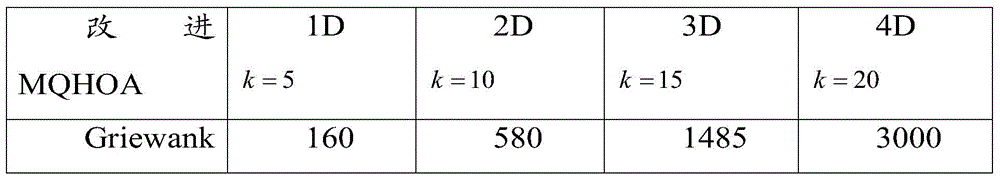
Owner:SOUTHWEST UNIVERSITY FOR NATIONALITIES
Improved index encryption algorithm and system
ActiveCN111556072AImprove securityIncrease the difficulty of crackingMultiple keys/algorithms usageData packAlgorithm
The invention provides an improved index encryption algorithm and system. The method comprises: indexing the first encryption array based on the first index data and the first data direction, sendingthe improved index data packet containing the first index data indication information to a receiving end computer; introducing a weight configuration function, an encrypted data pointing function andan encrypted data array feedback function into a computer cloud cluster; setting a special node for simultaneously processing a computer terminal data request needing to be encrypted in a cloud cluster, a first encryption array sent by an encryption array management node and a first data direction sent by a collaborative management node; separating the multi-source data and performing ternary combination, and obtaining different components of the encryption parameters from different nodes respectively, so that a receiving end computer can prompt corresponding first index data from the hidden pointer position of the index data packet.


Owner:深圳市今古科技有限公司
Method for calculating power flow of distribution network containing grid connection of new energy
InactiveCN107171329AIteration is simpleImprove computing efficiencySingle network parallel feeding arrangementsPhotovoltaic energy generationPower flowNew energy
The invention relates to a method for calculating the power flow of a distribution network containing grid connection of new energy, which belongs to the field of new energy power generation and relates to calculation for the power flow of a distribution network. The method comprises the steps of 1) acquiring original data from a system node parameter table, a branch parameter table and a new energy parameter table; 2) enabling the acquired original data to be equivalent into different types of nodes according to the type of the new energy; 3) converting PV-type new energy and PI-type new energy in the step 2) into PQ-type new energy capable of being processed; 4) correcting active power and reactive power of each node in the step 2); and 5) calculating voltage of each node in the step 2) by adopting an improved forward-backward sweep algorithm, terminating the calculation if a maximum value of the voltage difference of adjacent two times of iterations of all nodes satisfies certain precision and outputting a result, otherwise, continuing the iterative calculation. The method can give consideration to grid connection of all kinds of different new energy at the same time; and the method is simple in iteration, small in number of iteration times and high in calculation efficiency.


Owner:SUQIAN POWER SUPPLY COMPANY OF JIANGSU PROVINCE POWER +2
Weather particle rendering method and device, computer equipment and storage medium
PendingCN110473279AIteration is simpleEasy to modifyVideo games3D-image renderingData subjectComputer equipment
The invention provides a weather particle rendering method and device, computer equipment and a storage medium. The device comprises: a script execution module which is used for triggering a weather situation change signal when a weather situation change condition is satisfied, and executing a target code corresponding to target weather in a particle generation script, so as to transmit particle data corresponding to weather particles of the target weather to a particle processing module; a particle processing module which is used for performing format conversion on the particle data after receiving the particle data transmitted by the script execution module, and submitting the particle data subjected to format conversion to a graphic processing module; and the graphic processing module which is used for generating and rendering a particle instance based on the real-time position information of the virtual camera and the particle data subjected to format conversion so as to present aweather scene corresponding to the target weather in the game scene. According to the method, the rendering execution logic of the weather particles can be iterated more easily.


Owner:NETEASE (HANGZHOU) NETWORK CO LTD
Micro-power-grid scheduling method based on quantum-behaved particle swarm optimization
ActiveCN105470947AIteration is simpleImprove search abilityForecastingAc network load balancingPower balancingPower grid
The invention discloses a micro-power-grid scheduling method based on quantum-behaved particle swarm optimization. The invention aims at a grid-connected wind and light storage micro power grid power balance constraint problem. Currently, a penalty term is added in a target function; the penalty term is added in a corresponding target function value of particles deviating power balance so that a function value is increased; and through algorithm optimization, the particles are filtered. In this case, a quantity of the particles is reduced and searching performance of the algorithm is influenced. In the invention, a storage battery is taken as a direct optimization variable and microgrid and large power grid exchanging power is taken as an indirect optimization variable; through the above mode, particle dimensions are reduced; reinitialization and loop iteration are performed on particles which do not satisfy a charged state constraint and particles which do not satisfy a large power grid exchanging power constraint so that the searching performance of the particles is guaranteed and a convergence speed can be correspondingly increased.


Owner:芜湖数字信息产业园有限公司
Airborne storage device test system
The invention discloses an airborne storage device test system, comprising a test input module, a test software module and a test report output module. The test software module loads a test object program file into the airborne storage device. The test input module sends the received test type and the corresponding test parameters to the test object program file. After receiving the test type andthe corresponding test parameters, the test object program file generates excitation data according to the test type and executes the corresponding test operation, and transmits the test result to thetest report output module. The test report output module is used for parsing the received test results and generating test reports. In the invention, the tester only needs to input parameters such astest type according to the menu, the test system carries out automatic test and outputs test report in the whole process, and can carry out comparative analysis, compared with the traditional test system, the efficiency is greatly improved.


Owner:CHINESE AERONAUTICAL RADIO ELECTRONICS RES INST
Voice playback method and device based on boarding applications
PendingCN110299130AIteration is simpleEasy to combineSound input/outputSpeech synthesisSpeech soundOptimal combination
The invention aims to provide a voice playback method and device based on boarding applications. The voice playback method comprises the steps that a control panel is called on the basis of preset operation of a user on current text in a browser, the control panel comprises one or more inlets of the boarding applications, wherein the boarding applications are used for conducting voice playback onthe text; the target boarding application determined from the one or more boarding applications by the user is obtained, and the current text is sent to the target boarding application; voice information returned by the target boarding application is received, and the voice information is determined in a synthesized mode by network equipment corresponding to the target boarding application according to the voice playback mode associated with the target boarding application and the current text; and the voice information is played back through a playback interface of the browser. Thus the reading mode is selected through the showing mode of the boarding applications, voice is synthesized through the network equipment, and thus the optimal combination effect of voice reading is achieved.


Owner:SHANGHAI LIANSHANG NETWORK TECHNOLOGY CO LTD
Inverse treatment planning method of treatment plan and treatment planning system
InactiveCN102184318AIteration is simpleEfficient iterative processGenetic modelsSpecial data processing applicationsInitial treatmentMedicine
The invention discloses an inverse treatment planning method of a treatment plan. The method comprises the following steps of: A, inputting a medical image of a patient; B, drawing tissue outlines of a body surface, a target body and injured organs of the patient; C, setting an inverse planning target; D, creating an initial treatment plan; E, setting iterative optimization parameters; F, generating an individual treatment plan; G, calculating a dose field of the individual treatment plan; H, selecting a current optimum plan according to the dose field; I, executing the step L if a difference value between the current optimum plan and the inverse planning target is smaller than a preset first threshold value, or executing the next step; J, executing the step L if the number of times of evolution is equal to the number of frequencies of population evolution, or executing the next step; K, evolving generation to new-generation population by mating and / or variation, and executing the step G; and L, stopping the population evolution and outputting the current optimum plan. The invention also discloses a treatment planning system. By adoption of a population evolution method based on a gene algorithm, iteration is carried out by a mating or variation method, so that the whole iterative process is simple and efficient.


Owner:SHEN ZHEN HYPER TECH SHENZHEN
An SDK for displaying and editing three-dimensional models
ActiveCN109544701AAchieve interactionFlexible secondary developmentImage data processingComputer graphics (images)Modularity
The present invention provides an SDK for displaying and editing three-dimensional models. At least, that SDK comprises the following step: a process design of an SDK state mechanism; Data structure design, including individual model data for objects or scenes, and work data for scenarios, decomposing logical relationships between models and scenes; The server data management module ServerData encapsulates the loading process and encapsulates the interaction logic. Based on model presentation and model interaction, the SDK designs modular model data and work data, which is independent and easyto reach, and can realize the rapid display and editing of three-dimensional model in mobile terminal.


Owner:CHANGSHA MORALE NETWORK TECH CO LTD
An optimization method of implicit curved surface porous structure
ActiveCN109145409AMaximize specific surface areaFast convergenceGeometric CADSpecial data processing applicationsLocal optimumParticle position
The invention discloses an optimization method of an implicit curved surface porous structure, which comprises the following steps of: inputting an optimization implicit curved surface function expression, the implicit curved surface porous structure relative density, the particle swarm size and the maximum iteration number; initializing particles, each particle position coordinate including curvature parameter and wall thickness parameter of the implicit curved surface porous structure; calculating the constraint fitness of the iterative particle; Updating the local optimal position and the global optimal position in the particle swarm; calculating the update position of each particle by linear weighting; the curvature parameter in the particle position being the inverse number when the catastrophe requirement is satisfied; when the maximum number of iterations is exceeded, the iteration being stopped, the optimal particle position being output, and the implicit curved surface porousstructure corresponding to the optimal parameters being generated. In the method, the particle is iterated by linear weighting, and the catastrophe probability is added to ensure the random behavior of the particle. The iteration speed of the method is fast, and the curvature parameter and the wall thickness parameter are obtained by iteration, which can generate the implicit curved surface porousstructure satisfying the multi-functional requirements.


Owner:ZHEJIANG UNIV
Plug-and-play large-scale efficient robust phase recovery method and system
ActiveCN112163186AImprove efficiencyNoise robustnessImage enhancementImage analysisAlgorithmModularity
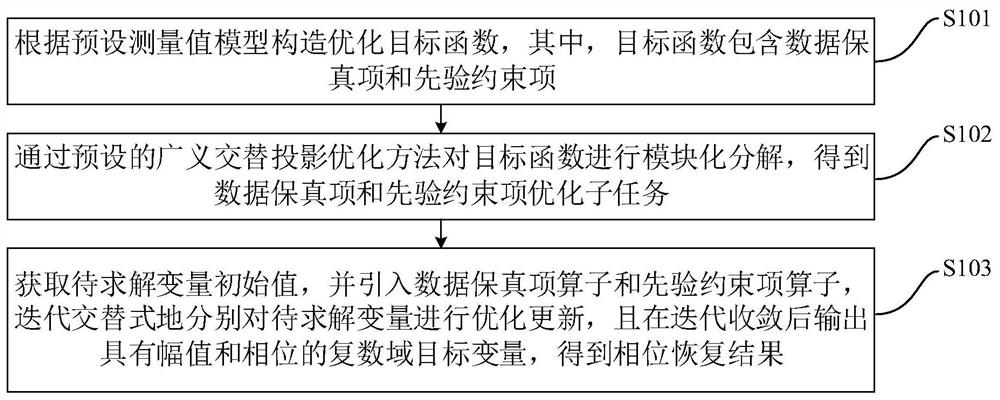
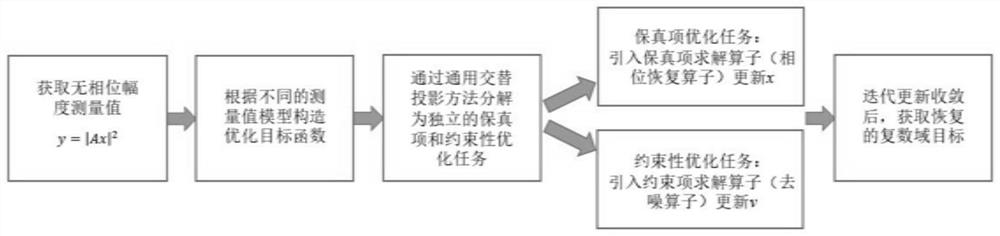
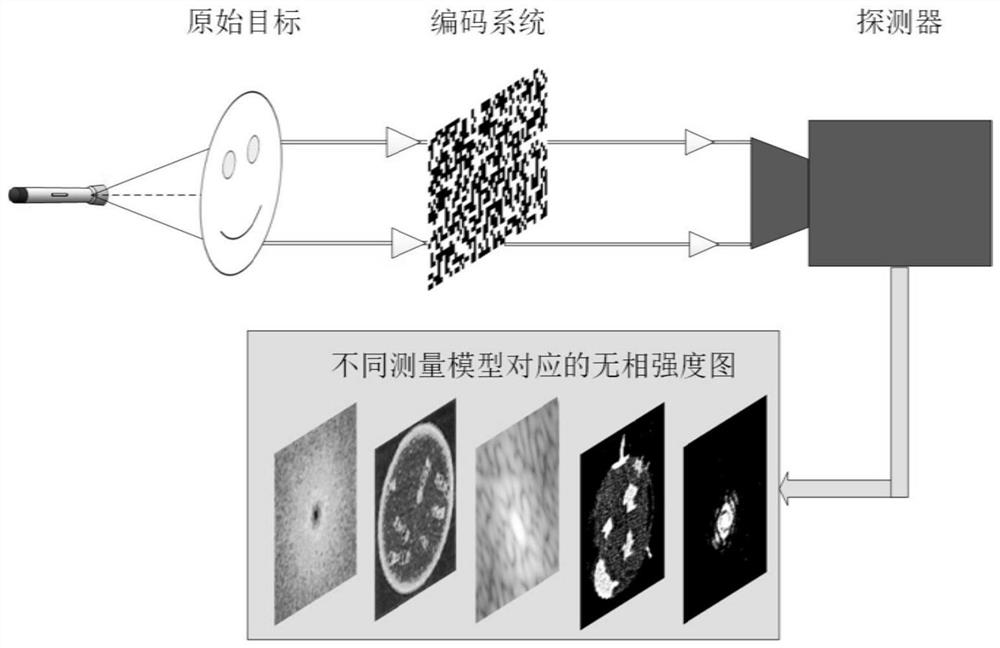
The invention discloses a plug-and-play large-scale efficient robust phase recovery method and system, and the method comprises the following steps: constructing an optimization target function according to a preset measurement value model, wherein the target function comprises a data fidelity term and a priori constraint term; performing modular decomposition on the target function through a preset generalized alternate projection optimization method to obtain data fidelity term and prior constraint term optimization subtasks; and obtaining an initial value of a variable to be solved, introducing a data fidelity term operator and a priori constraint term operator, iteratively, alternately and respectively optimizing and updating the variable to be solved, and outputting a complex domain target variable with an amplitude and a phase after iterative convergence to obtain a phase recovery result. According to the method, iterative updating is simple and rapid, a flexible and variable priori constraint item operator is introduced, and the problem of large-scale phase recovery can be efficiently solved.
Owner:BEIJING INSTITUTE OF TECHNOLOGYGY
GaN compatible driving circuit
PendingCN113708749AIteration is simpleStrong competitivenessElectronic switchingEfficient power electronics conversionPhysicsMOSFET
The invention discloses a GaN compatible driving circuit, and belongs to the technical field of semiconductor devices, the GaN compatible driving circuit comprises a driving chip IC, an MOS driving module and a GaN driving compatible module, the driving end of the driving chip IC is connected with the input end of the MOS driving module, the GaN driving compatible module comprises a voltage limiting unit, an acceleration unit and a voltage dividing unit, the input end of the voltage limiting unit is connected with the output end of the MOS driving module, the output end of the voltage limiting unit is connected with the input end of the voltage dividing unit and the grid electrode of the N-type field effect transistor, the output end of the voltage dividing unit is connected with the source electrode of the N-type field effect transistor and the driving chip IC, and the acceleration unit is connected with the voltage limiting unit in parallel. The method has the effect that the GaN and the silicon-based MOSFET can be driven in a compatible mode.
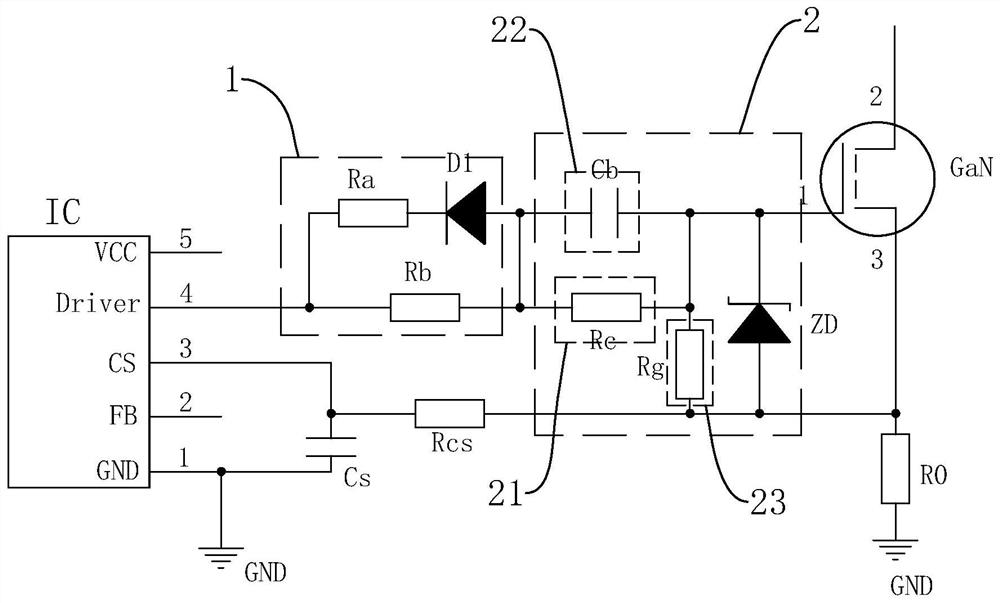
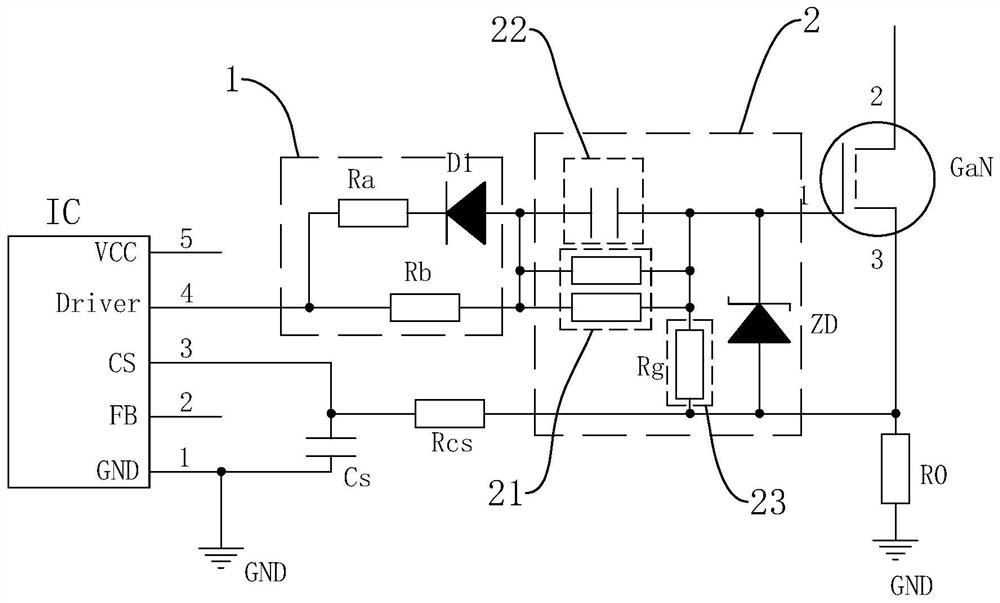
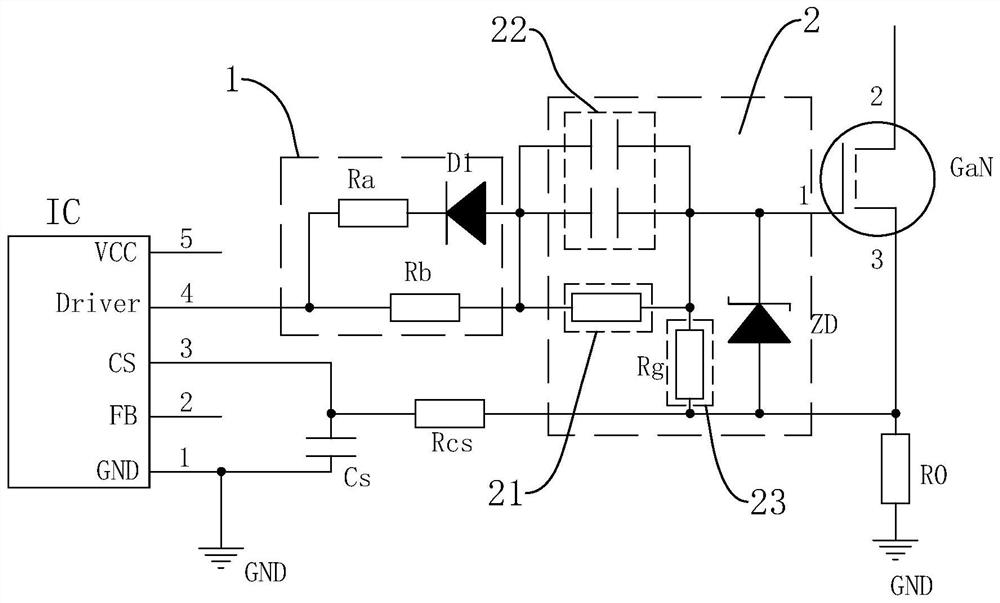
Owner:SHENZHEN FAHOLD ELECTRONICS CO LTD
Path planning control system for easily extended stereo garage
InactiveCN106647404ARich expansion possibilitiesIteration is simpleProgramme control in sequence/logic controllersMovement controlPath plan
The invention provides a path planning control system for an easily extended stereo garage, and the system comprises a control execution module, a basic control module, a movement control module, an instruction switching module, a path planning module and a plugboard interface. The control execution module is connected with the basic control module, the movement control module, the instruction switching module and the path planning module, and the control execution module and the basic control module are solidified on one circuit board. The control execution module sequentially transmits loading code instructions to the basic control module, the movement control module, the instruction switching module and the path planning module. The basic control module stores the basic codes of the whole operation. The system can provide abundant extending possibilities for a stereo garage through the control execution module, the basic control module, the movement control module, the instruction switching module, the path planning module and the plugboard interface. Only if circuit boards inserted at the plugboard interface are increased or replaced, can a manufacturer carry out the updating of a product easily and can a user carry out the upgrading and updating of the control function of the product.

Owner:GUIZHOU AEROSPACE NANHAI SCI & TECH
Alternating current control cabinet and design method thereof, electronic equipment and storage medium
PendingCN119442501ARealize cost reduction and efficiency increaseIteration is simpleElectrical storage systemGeometric CADThermodynamicsProcess engineering
The invention is suitable for the technical field of energy storage, and provides an alternating current control cabinet and a design method thereof, electronic equipment and a storage medium, and the method comprises the steps: determining the parameters of an energy storage converter according to the input information of an energy storage system; determining a design scheme of the AC control cabinet according to the design requirements of the AC control cabinet, the parameters of the energy storage converter and the principle of lowest cost; calculating heat dissipation parameters according to the design scheme; and outputting a design scheme under the condition that the heat dissipation parameters meet the heat dissipation requirements, and repeatedly executing calculation of the heat dissipation parameters according to the design scheme and subsequent steps after the design scheme is adjusted under the condition that the heat dissipation parameters do not meet the heat dissipation requirements.

Owner:NANJING LINGTAN INTELLIGENT TECH CO LTD
Positioning method based on single anchor node positioning system and terminal
ActiveCN119450692AIncrease signal powerreduce complexitySpatial transmit diversityPosition fixationSimulationOptimization problem
The invention relates to a positioning method based on a single anchor node positioning system and a terminal, and the method comprises the following steps: S1, introducing an intelligent reflection surface into the single anchor node positioning system, forming a high-power indirect path, and building a signal model of the single anchor node positioning system based on the intelligent reflection surface; s2, establishing an optimization problem based on the model, and estimating parameters of the distance, the speed and the angle of arrival of the user; and S3, realizing positioning of the user based on parameter estimation of the user. Compared with the prior art, the method has the advantages that the high-power indirect path is realized by introducing the intelligent reflecting surface, the positioning deviation caused by the synchronization error of the user side and the base station side is removed, and the multi-path parameter estimation and the user positioning are realized by designing a low-complexity algorithm.

Owner:SOUTHEAST UNIV +1
Guidance rocket inner trajectory matching parameter design method for reducing peak heat flow
InactiveCN119358201AImprove acceleration characteristicsAdd Design DimensionsDesign optimisation/simulationConstraint-based CADExternal ballisticsInternal ballistics
The invention discloses a guided rocket inner ballistic proportioning parameter design method for reducing peak heat flow, which puts forward design requirements on guided rocket engine inner ballistic parameters from the perspective of overall design, introduces inner ballistic curve proportioning parameters, and realizes reduction of outer ballistic peak heat flow by optimizing the proportioning parameters. The matching parameters are iterated through a double-loop optimization framework, the outer loop aims at reducing peak heat flow, the inner loop is rapidly evaluated through a ballistic optimization method, and the optimal matching parameters of the inner ballistic of the guided rocket engine are rapidly obtained. According to the method, integrated design of the inner trajectory and the outer trajectory of the guided rocket is achieved, the design dimension of the guided rocket is increased, a new scheme optimization approach is provided for overall designers, and the adaptation degree of an overall scheme and an engine scheme is improved.

Owner:XIAN MODERN CONTROL TECH RES INST
Rapid generating method of wire rope pulley mechanism
InactiveCN106354961ARapid designQuick changeGeometric CADSpecial data processing applicationsDesign standardSystems design
The invention relates to a rapid generating method of a wire rope pulley mechanism. The method includes the steps of designing input, inputting an optimization target, determining interface parameters, rapidly obtaining the optimization result of mechanism design parameters, transmitting the optimization result to a parameterization model of a CAD platform in a cross-platform mode, and automatically generating a mechanism digital model through parameterization of the CAD platform so as to rapidly optimize parts of the wire rope pulley mechanism. By means of the method, the iterative process in traditional design can be simplified, the rapid design and change of the parts of the wire rope pulley mechanism are achieved, and the optimal solution is found to meet the related system design requirements, design standards and boundary conditions.


Owner:COMAC +1
Electrocardiogram data classification method, device and system
ActiveCN112545525BSolve inaccurateIteration is simpleDiagnostic recording/measuringSensorsEcho state networkClassification methods
The present invention provides a method, device and system for classifying electrocardiogram data, wherein the method includes: using the echo state network to convert the electrocardiogram data to be classified into electrocardiogram model data; inputting the electrocardiogram model data to a pre-trained normal classifier, and obtaining the first A classification result; input the electrocardiogram model data to one or more pre-trained abnormal classifiers, and obtain one or more second classification results; for the second classification result output by each abnormal classifier: if the first If the classification result indicates that the ECG model data is normal and the second classification result indicates that the ECG model data is not abnormal, then it is determined that the ECG data to be classified is normal; if the first classification result indicates that the ECG model data is abnormal and the second If the result of the binary classification indicates that the data of the electrocardiogram model is abnormal, it is determined that the data of the electrocardiogram to be classified is abnormal. This application can accurately judge the electrocardiogram data and improve the accuracy.


Owner:UNIV OF SCI & TECH OF CHINA
An Analytical Calculation Method Applicable to Geostationary Satellite Fixed-point Control Planning
ActiveCN113968361BConcise analytical solutionIteration is simpleCosmonautic vehiclesSpacecraft guiding apparatusPulse controlGeosynchronous satellite
The present invention is an analytical calculation method suitable for a geosynchronous satellite fixed-point control plan, which is specifically implemented according to the following steps: step 1, establishing a fixed-point capture orbit control model, and determining control target variables and design variables; step 2, establishing a fixed-point capture orbit control model according to the Fixed-point capture control terminal constraint model; Step 3, determine the three-pulse constraint model according to the fixed-point capture orbit control model and the fixed-point capture control terminal constraint model, and calculate the size of the three-pulse and its control timing; Step 4, use the perturbation iteration method to determine Three-pulse control parameters that satisfy terminal conditions under full perturbation conditions. The invention establishes a three-pulse constraint model through the fixed-point capture orbit control model and the fixed-point capture control terminal constraint model, and can cover all possible working conditions of the fixed-point capture control through three situations, and the iterative process is simple, and it can converge to 2-3 times. The target value, the process is simple, and the amount of calculation is small.


Owner:CHINA XIAN SATELLITE CONTROL CENT
Evaluation Method of Non-parallel Storage Life Test Based on Feasible Region Selection of Acceleration Factor
ActiveCN104680005BGuaranteed accuracyIteration is simpleSpecial data processing applicationsSelection biasOperability
A non-parallel storage life test evaluation method based on the selection of the acceleration factor feasible region, the steps are as follows: Step 1: Calculate the acceleration factor and the comprehensive failure time; Step 2: Discuss the acceleration factor feasible region; Step 3: Use the best linear Partial estimation method for parameter selection; Step 4: Calculate the point estimation and interval estimation of the logarithmic reliable life. The present invention aims at the phenomenon of missing storage data in the life evaluation of non-parallel storage products. On the basis of the service life obeying the Weibull distribution, the storage data and the test data are integrated through the acceleration factor, and the data are fully utilized for calculation, ensuring the accuracy of the life model parameter estimation. Accuracy, its algorithm has lower requirements on the initial value of the parameters, the algorithm iteration is fast and simple, and the operability is strong.


Owner:BEIHANG UNIV
An Improved Index Encryption Algorithm and System
ActiveCN111556072BImprove securityIncrease the difficulty of crackingMultiple keys/algorithms usageData packAlgorithm
The invention provides an improved index encryption algorithm and system. The method comprises: indexing the first encryption array based on the first index data and the first data direction, sendingthe improved index data packet containing the first index data indication information to a receiving end computer; introducing a weight configuration function, an encrypted data pointing function andan encrypted data array feedback function into a computer cloud cluster; setting a special node for simultaneously processing a computer terminal data request needing to be encrypted in a cloud cluster, a first encryption array sent by an encryption array management node and a first data direction sent by a collaborative management node; separating the multi-source data and performing ternary combination, and obtaining different components of the encryption parameters from different nodes respectively, so that a receiving end computer can prompt corresponding first index data from the hidden pointer position of the index data packet.


Owner:深圳市今古科技有限公司
Modeling method for radar complex electromagnetic environment effect mechanism
ActiveCN111709187AImprove combat capabilityEffective modelingCharacter and pattern recognitionDesign optimisation/simulationRadar systemsSensitive analysis
The invention discloses a modeling method for a radar complex electromagnetic environment effect mechanism. The method provided by the invention comprises the following steps: firstly, performing Bayesian network structure learning on effect data of each subsystem of a radar in an electromagnetic environment by using a K2 algorithm, and establishing a Bayesian network topological structure of a radar system from an input element to an output element; then, under the condition that the network structure is known, calculating Bayesian network parameters by adopting a maximum likelihood estimation algorithm; then, after the Bayesian network model is obtained, performing sensitivity analysis based on the conditional probability change degree on the radar electromagnetic environment effect; andfinally, performing probabilistic reasoning on the model of the radar complex electromagnetic environment effect mechanism by adopting a connection tree reasoning algorithm. According to the method,the radar complex electromagnetic environment effect mechanism can be effectively modeled, the modeling precision is 91%, and theoretical support is provided for improving the combat ability of the radar in the complex electromagnetic environment.


Owner:XIAN TECHNOLOGICAL UNIV
Single-diagonal implicit Runge-Kutta method for simulating second-order differential equation and application
PendingCN119294123Areduce the number of iterationsImprove computing efficiencyDesign optimisation/simulationComplex mathematical operationsSecond order differential equationsComputational physics
The invention discloses a single diagonal implicit Runge-Kutta method for simulating a second-order differential equation, and the method comprises the steps: obtaining a simulated second-order differential equation, converting the simulated second-order differential equation into a target nonlinear equation, calculating a Jacobian matrix, constructing an iteration matrix, and carrying out the decomposition of the Jacobian matrix; predicting the solution of the next time step of the target nonlinear equation by using the explicit part of the single diagonal implicit Runge-Kutta; the prediction result is used as an initial value of Newton iteration, a single diagonal implicit Runge-Kutta method is adopted in the iteration process, the prediction result is corrected to solve a target nonlinear equation, and iteration steps are repeated until a preset convergence condition is met; performing error estimation and calculation according to a solving result to obtain a new step length, if an error meets a preset condition, advancing a time step, updating the step length and a solution of the target nonlinear equation, otherwise, only updating the step length and returning to execute calculation of the Jacobian matrix. Second-order differential equations of specific categories can be solved more effectively, and stability, precision and efficiency of numerical calculation are improved.

Owner:SHANGHAI JIUTONGFANG TECHNOLOGY CO LTD